Executives from Werner Enterprises outlined a path to double-digit truckload margins, however mentioned value headwinds will possible restrict progress over the subsequent two quarters.
Werner (NASDAQ: WERN) reported third-quarter adjusted earnings per share of 16 cents after the market closed on Tuesday. The consequence was in keeping with a revenue warning issued earlier within the month, calling for adjusted EPS of 15 to 16 cents versus the 36-cent consensus estimate on the time.
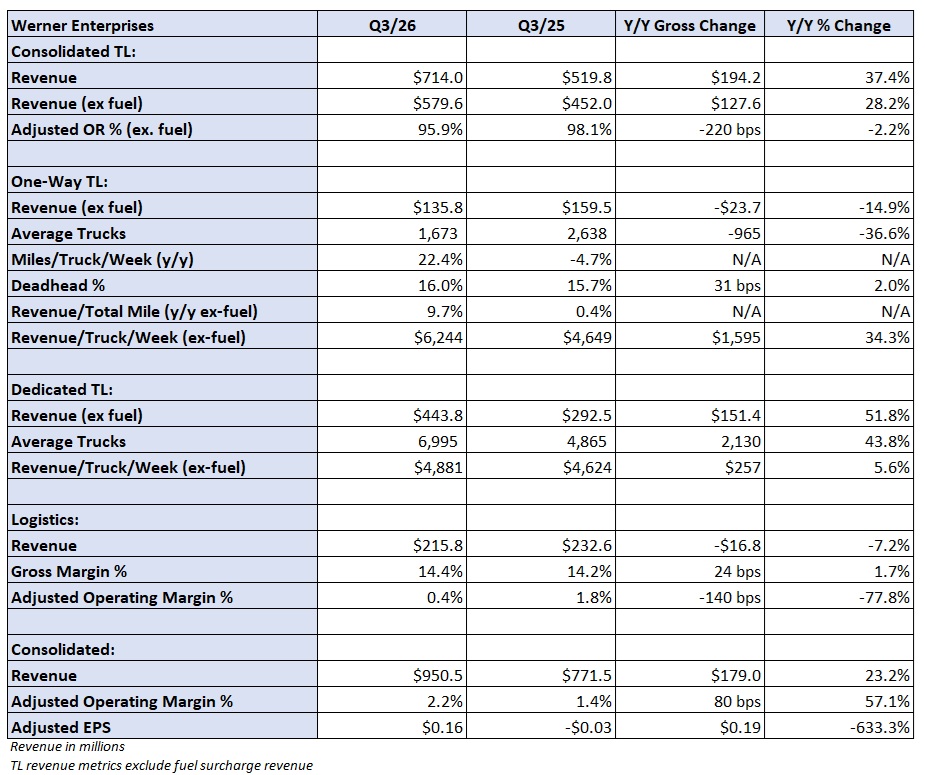
Consolidated income of $951 million was 23% larger 12 months over 12 months and on the prime finish of administration’s revised outlook ($946 million to $951 million). The rise was largely because of larger gas surcharges and the January acquisition of devoted provider FirstFleet.
EPS bridge from Q3 to This autumn
Sequential value will increase from elevated diesel gas costs, larger driver procurement bills and a reserve adjustment for prior claims have been an 18-cent EPS drag on the third quarter. Features on asset gross sales elevated y/y from $4.5 million to $8 million, offering a 4-cent tailwind. (The corporate booked an adjusted internet lack of 3 cents per share within the 2025 third quarter.)
Werner mentioned some prices, like driver recruiting and coaching, have been front-loaded bills incurred forward of a income offset. As an example, it needed to bear the prices of including 130 devoted vehicles and drivers all through the quarter, though the income stream didn’t start till the top of the interval.
“We made the deliberate determination to speed up investments in driver recruiting and onboarding to seize rising buyer demand and help fleet growth as trade capability tightens,” mentioned Chairman and CEO Derek Leathers. “We stay assured in our trajectory and our capability to capitalize on the early levels of this freight upcycle.”
Nevertheless, it additionally mentioned some value headwinds will linger into the primary quarter.
It offered a mushy information for “modest sequential [EPS] enchancment” within the fourth quarter (from the 16-cent consequence within the third quarter). However the consequence will in all probability be materially under the present 38-cent fourth-quarter consensus estimate.
Roughly one third of the 18-cent third-quarter EPS drag was tied to driver recruiting and sign-on bonuses, and doesn’t characterize “structural labor inflation,” administration mentioned. The remaining 12 cents stemmed from gas and insurance coverage claims, which ought to largely dissipate within the fourth quarter. Nevertheless, decrease features on sale (guided to complete simply $1.7 million), larger curiosity expense and the next tax charge are further headwinds. Higher pricing and a barely bigger fleet to accommodate peak season demand will present some offsets.
Truckload gas surcharges function on a one-week lag. Diesel costs have been up sequentially in 9 of the 13 weeks of the third quarter. By month, retail diesel costs dipped 1% sequentially in July, however elevated 10% sequentially in August and one other 15% in September. The near-term headwind will develop into an earnings tailwind when diesel costs revert.
Different Q3 takeaways
The corporate’s devoted phase (81% of its complete truck fleet) reported a 52% y/y enhance in income (ex-fuel) as the common truck depend was up 44% y/y to almost 7,000 items and income per truck per week (ex-fuel) elevated 6% y/y. (The FirstFleet deal added over 2,400 tractors and $615 million in annual income.)
Devoted income per truck per week is now anticipated to extend by 4 to five% y/y for full-year 2026, a rise from the prior outlook for a 3-to-5% enhance.
The one-way unit once more noticed huge features in utilization following a restructuring earlier within the 12 months, which included exiting non-profitable accounts and repurposing under-utilized tools. One-way income was down 15% y/y (ex-fuel) as the common truck depend declined 37% y/y. Income per truck per week (ex-fuel) elevated 34% y/y as miles per truck elevated 22% and income per complete mile (ex-fuel) elevated 10%. The speed-per-mile metric was negatively impacted by a 116-mile enhance in size of haul. (Longer hauls normally accompany decrease per-mile charges.)
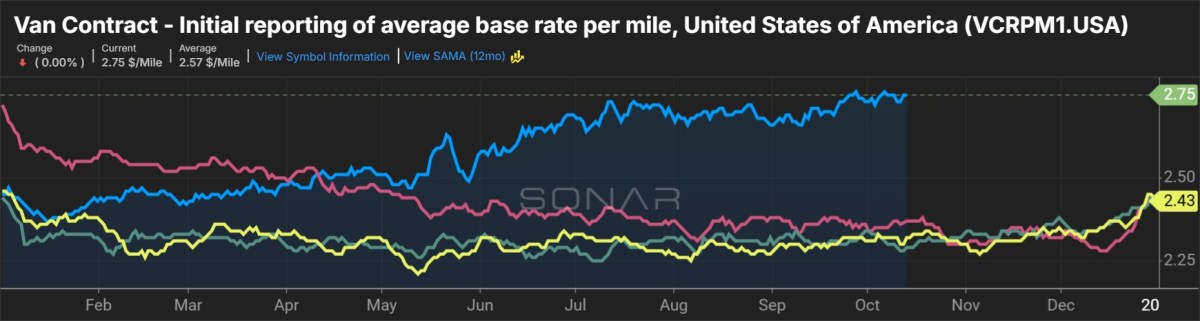
Steerage for the one-way fleet once more requires a 10-to-13% y/y enhance in income per complete mile through the fourth quarter. Roughly 60% of the one-way income e book renews within the first half of 2027. Administration is eyeing double-digit will increase on many of those renewals.
One-way noticed greater than 800 foundation factors of y/y margin enchancment within the quarter (precise margin not disclosed). Werner is once more trying to develop this fleet.
The TL unit recorded $714 million in mixed income, a 37% y/y enhance (up 28% y/y excluding gas surcharges). A 95.9% adjusted working ratio (4.1% adjusted working margin) was 220 bps higher y/y, however 140 bps worse than the prior quarter. Administration mentioned the sequential value headwinds represented a 200-bp drag.
The corporate’s logistics unit reported a 7% y/y income decline to $216 million, however returned to profitability, posting a 0.4% adjusted working margin. Truckload brokerage, which operates inside the logistics unit, booked 600 bps of sequential working margin enchancment. (Werner doesn’t disclose this subsegment’s margin outcomes.)
Why it issues? Werner’s third-quarter consequence exhibits the numerous value pressures carriers are at the moment dealing with—particularly rising diesel gas costs and better driver procurement prices. It alerts that the trade’s restoration won’t be linear, and that whereas carriers are elevating charges, profitability continues to be being squeezed by early-upcycle value inflation.
Extra BigRig articles by Todd Maiden:
- Knight-Swift once more eyes huge charge will increase as new bid season nears
- Heartland Specific sees earnings turnaround in Q3
- Werner Enterprises points Q3 revenue warning
The put up Werner Enterprises sees value headwinds lingering into Q1 appeared first on BigRig.