
Truckload and less-than-truckload price indexes established recent highs within the second quarter because the freight trade recovers from an almost four-year downturn. Charges are anticipated to proceed to maneuver up and to the proper within the third quarter, in response to a Tuesday report from 3PL AFS Logistics and monetary providers agency TD Cowen.
Provide-side correction favors giant TL carriers
Truckload charges hit a cycle excessive through the second quarter and are anticipated to step increased within the third quarter.
Capability constraints and a surge in diesel gas costs pushed the TL rate-per-mile element of the TD Cowen-AFS Freight Index to a 14-quarter excessive. The second-quarter rate-per-mile studying got here in 16% above the January 2018 baseline. That was up 6.6 share factors from the primary quarter and 10.1 factors increased yr over yr.
The index is predicted to extend to a stage that’s 17.7% above the baseline within the third quarter. That will be 11.7 factors increased y/y.
The report mentioned greater than 48,000 non-compliant drivers have been pressured out of the trade over the previous yr. It additionally mentioned small carriers could also be sitting on the sidelines on account of still-depressed economics and gas worth headwinds. (Most small carriers wrestle to recoup rising gas prices via surcharge packages.)
“Smaller truckload carriers engaged on tight margins might park vans and await gas costs to revert to extra palatable ranges earlier than returning to operation, additional restraining capability amid a supply-side market correction,” mentioned AFS Logistics CEO Andy Dyer.
Showing at an investor convention final month, public provider administration groups mentioned mini-bid exercise has spiked as routing guides crumble. They mentioned contractual charges set with shippers early within the 2026 bid season proved too low. The carriers are actually eyeing double-digit contractual price will increase this yr and subsequent to revive margins.
The Tuesday knowledge confirmed TL linehaul value per cargo elevated 3.1% sequentially within the second quarter regardless that miles per cargo fell 1.8%. The report famous a rise in shipments of 500 miles or much less, as some longer-haul strikes have been misplaced to cheaper intermodal choices.
Accelerated GRI schedule indicators LTL provider pricing energy
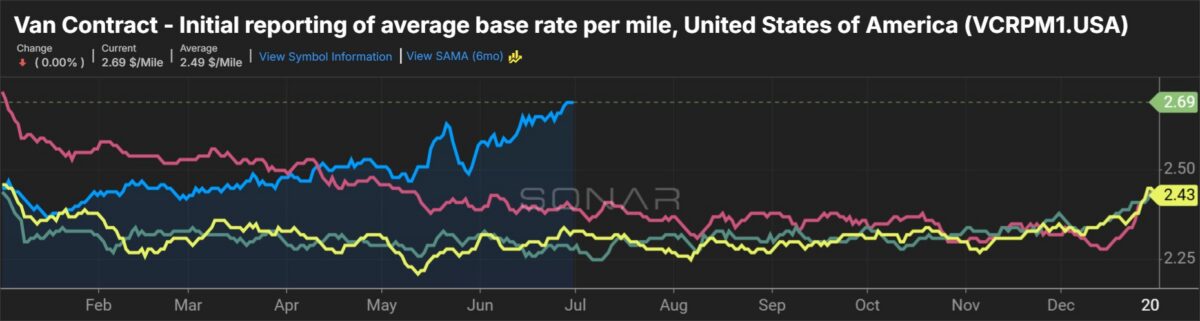
A gradual drumbeat of contractual price will increase together with increased gas costs pushed the LTL rate-per-pound element of the index to an all-time excessive within the second quarter. Giant public carriers are additionally taking common price will increase earlier within the yr given favorable market fundamentals.
The index stood 76.5% above the 2018 baseline within the second quarter. That was 9.6 factors increased sequentially and 13.3 factors increased than the year-ago stage. Gas surcharges captured by the dataset have been greater than 60% above the June 2025 benchmark through the interval, as retail diesel costs have been 51% increased y/y. (Much less-than-truckload gas surcharge mechanisms embrace a step operate as diesel costs rise, usually leading to margin accretion.)
The index is predicted to extend 30 foundation factors sequentially within the third quarter, which might be almost 10 factors increased y/y.
“Q2 confirmed that carriers’ pricing methods embrace the power to not solely safe price will increase and strategically precious volumes, however seize risky gas prices,” mentioned Mich Fabriga, vp of LTL pricing at AFS Logistics.
Common price will increase (GRIs), which often apply to one-quarter of provider shipments, have once more been pulled ahead from a typical annual cadence.
ArcBest (NASDAQ: ARCB) carried out a 5.9% GRI on June 22. The rise was flat y/y however put in roughly six weeks forward of the 2025 price hike. Saia (NASDAQ: SAIA) carried out a 7.1% GRI on July 6. The rise was 120 bps increased and three months sooner than final yr’s bump.
The report confirmed LTL value per cargo was up 0.7% sequentially within the second quarter regardless that weight per cargo fell 4.8%. Elevated gas costs have been behind the rise in prices.
Public carriers reported y/y will increase in weight per cargo throughout April and Might. XPO (NYSE: XPO) was the outlier, however the firm’s freight combine now consists of extra shipments from SMBs, which are inclined to have decrease cargo weights however higher margins.
The heavier cargo weights are on account of weak prior-year comps and as some freight misplaced to a depressed TL market comes again. Additionally, industrial exercise improved for a sixth consecutive month in June, in response to manufacturing knowledge launched by the Institute for Provide Administration. The info usually leads LTL volumes by a number of months, as roughly two-thirds of provider income is tied to industrial output.
(Two-year-stacked tonnage comparisons, which clean out prior-year volatility, turned constructive for public LTL carriers in Might following a protracted downturn.)
The report flagged FedEx Freight’s (NYSE: FDXF) narrowed industrial focus as a standalone entity and Amazon’s (NASDAQ: AMZN) full entry into LTL as potential headwinds for pricing.
The second-quarter earnings season begins Wednesday when J.B. Hunt Transport Providers (NASDAQ: JBHT) studies after the market closes.
AFS Logistics is a non-asset-based 3PL offering audit and value administration providers, managed transportation, and freight brokerage. It has visibility into greater than $39 billion in annual freight spend.
Extra BigRig articles by Todd Maiden:
- Knight-Swift opens 4 LTL terminals
- Analysts increase TL, LTL estimates forward of Q2 earnings season
- STG Logistics exits Chapter 11 as intermodal market heats up
The submit TL, LTL charges to hit new highs in Q3 appeared first on BigRig.