
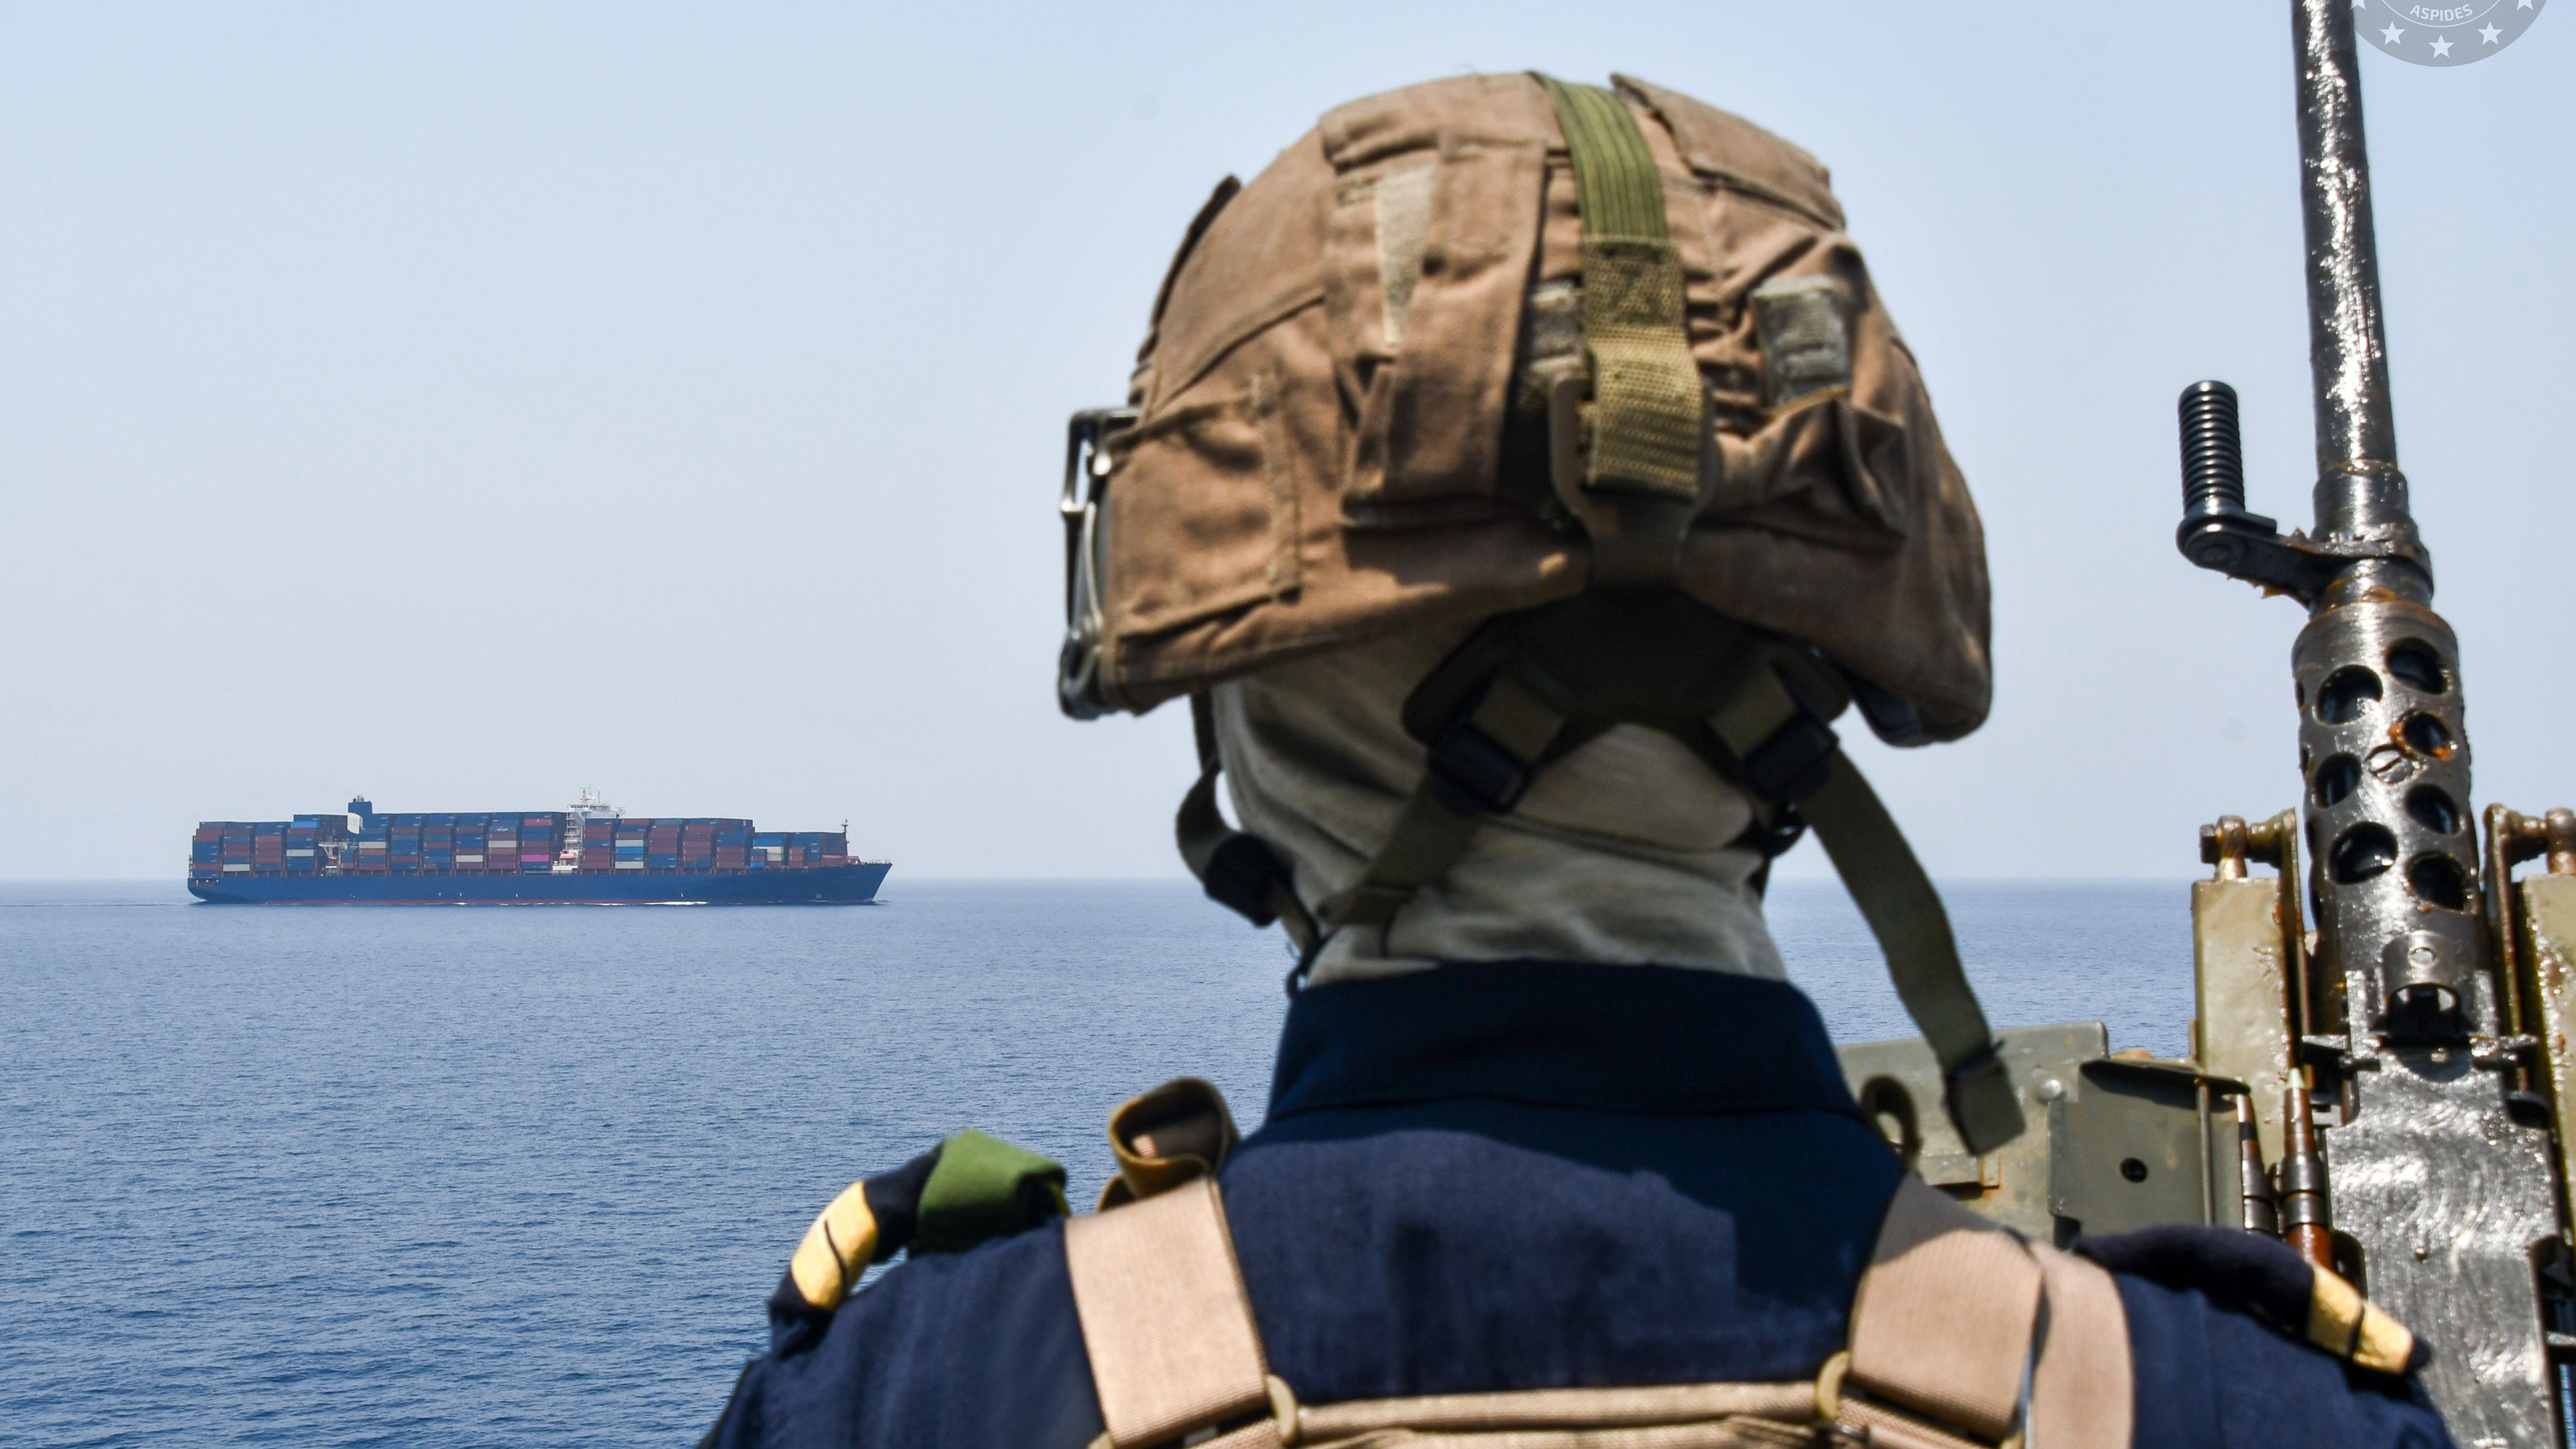
Container strains are restoring extra Suez Canal and southern Crimson Sea capability regardless of a widening Houthi risk on the Suez Canal route, a shift that’s serving to carry down Asia-Europe spot charges however leaves carriers and cargo homeowners uncovered to renewed disruption.
The Iran-backed Houthis motion not too long ago seized a strategic port and island instantly on the Bab el-Mandeb Strait on the south finish of the Crimson Sea, analyst and SONAR information supplier Freightos (NASDAQ: CRGO) mentioned in a analysis word. The territorial advance adopted an assault final week on a key Saudi oil pipeline, including to considerations that regional escalation might place extra strain on oil and marine-fuel markets.
The Yemen-based terrorist militia had already demonstrated a capability to assault or deter service provider vessels within the Crimson Sea earlier than gaining management of coastal territory. However the newest advance consolidates its place close to one of many world’s most essential maritime chokepoints, linking the Crimson Sea with the Gulf of Aden and serving because the southern strategy to the Suez Canal.
The event comes as some observers warn that measures used to blunt energy-price shocks earlier within the battle — notably releases from strategic reserves — could also be shedding effectiveness. Oil and bunker gasoline costs have climbed again towards Could ranges, elevating the prospect {that a} additional disruption might translate right into a extra acute fuel-market disaster.
Crimson Sea capability returns
Regardless of some shipper pushback and the heightened safety risk, carriers are rising transits by the Crimson Sea and Suez Canal, notably on Asia-Mediterranean companies.
Sea Intelligence estimates that greater than one-quarter of Asia-Europe capability will transit the Crimson Sea in September. The return is most pronounced on the Asia-Mediterranean commerce, the place roughly 35% of headhaul capability and 50% to 60% of backhaul capability are anticipated to maneuver by Suez.
The restoration is continuing extra slowly on Asia-North Europe companies. About 6% of headhaul capability and 30% of backhaul capability had returned to the route, in response to the estimates.
The shift is important as a result of the Suez route shortens voyages relative to diversions round Africa. A sooner transit improves efficient vessel capability, reduces the variety of ships required to maintain a weekly community and may ease schedule strain — supplied the safety scenario holds.
Analysts have estimated 2 million container items’ value of capability might return to the Mideast commerce lane.
Asia-Europe spot charges fall
The increasing use of the Crimson Sea route, mixed with easing demand after the height delivery season, seems to be weighing on Asia-Europe container costs.
Asia-North Europe spot costs fell 3% final week to about $4,300 per forty foot equal unit (FEU), whereas Asia-Mediterranean charges dropped 12% to roughly $4,200 per FEU. Each day pricing on each lanes had eased to roughly $3,800 per FEU up to now this week.
The sharper decline on the Mediterranean commerce could mirror its bigger Crimson Sea capability restoration. Asia-Mediterranean costs have fallen about $3,000 per FEU from their July peak, in contrast with a roughly $2,000-per-FEU lower for Asia-North Europe charges.
Nonetheless, fee ranges stay elevated. Asia-North Europe pricing is greater than 20% above pre-peak-season ranges from mid-Could, whereas Asia-Mediterranean costs stay greater than 50% larger, in response to the information out there replace.
That resilience factors to persistent operational constraints regardless of the return of some Suez routings. Greater war-related gasoline prices and congestion at Far East load ports proceed to pressure schedules, whereas poor on-time efficiency and cargo backlogs might stay components after China’s Golden Week vacation and into October.
Congestion at North European hubs can also be influencing carriers’ willingness to return to the Crimson Sea. The shorter routing will help strains regain schedule time and deploy their fleets extra effectively, whilst terminals and inland networks stay underneath strain.
Trans-Pacific charges stay agency
On the trans-Pacific, spot charges edged larger final week and stay close to peak-season ranges.
Robust import demand, coupled with congestion in Asia, is constant to assist pricing. However the newest Nationwide Retail Federation outlook initiatives U.S. ocean import arrivals will decline 9% in October from September, adopted by one other lower in November, proof that cargo demand could already be starting to retreat.
Decrease demand alone could not produce a speedy correction in freight charges. Continued port congestion and service clean sailings throughout the vacation interval might constrain accessible capability sufficient to maintain pricing comparatively excessive whilst volumes soften.
Most carriers don’t look like making ready broad October basic fee will increase, although CMA CGM has introduced important peak-season surcharges, notably on South Asia-to-U.S. trades.
Why it issues: Carriers are regaining the shorter Suez route on the similar time that the route’s southern gateway is turning into extra susceptible.
Learn extra articles by Editor right here.
Learn extra:
Nearly 1 million TEUs in new report for this U.S. container gateway
SC Ports, Norfolk Southern broaden intermodal entry to Huntsville
BNSF, CPKC, and CSX to request broad entry to a mixed UP-NS community
Summer time wanes however railfreight stays sizzling
102 Dems to STB: Put labor first in UP-NS rail merger evaluate
The submit Houthi positive factors deepen threat as carriers restore Crimson Sea companies appeared first on BigRig.