
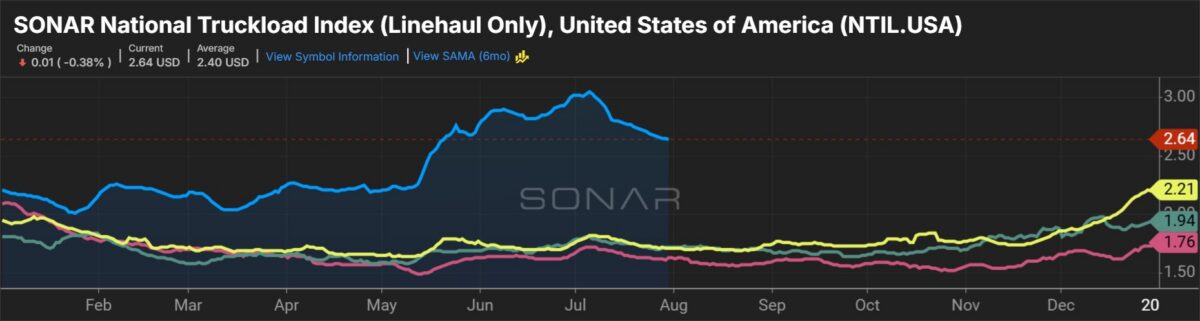
Multimodal transportation supplier Schneider Nationwide handily beat second-quarter expectations and raised its full-year earnings outlook. It stated a capability constrained truckload market is “solely within the early levels of fee restoration” and that it’s going to use the favorable imbalance to “recoup a number of years of serious price inflation.”
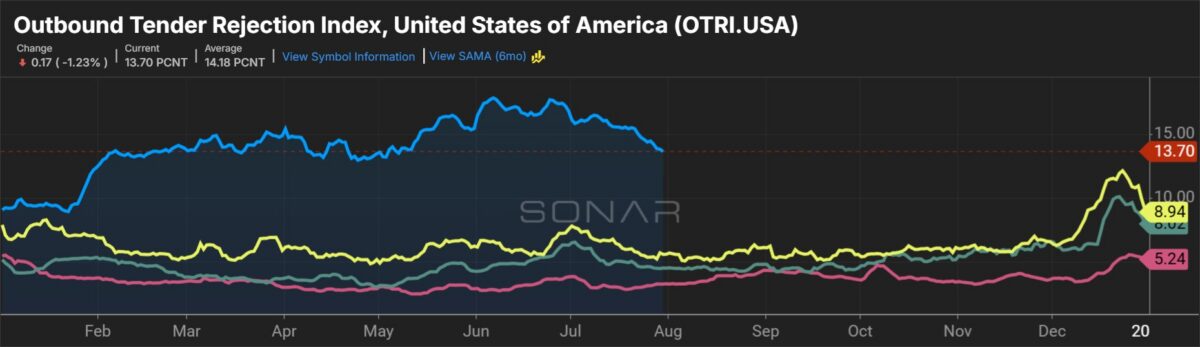
Schneider’s (NYSE: SNDR) community fleet (one-way) captured double-digit fee will increase on contract renewals within the quarter. Mini-bid exercise is up as shippers develop extra involved with securing capability for peak season. Schneider elevated its spot market publicity, noting June carefully resembled March 2021, the prior cycle peak.
Schneider reported adjusted earnings per share of 29 cents for the second quarter, which was 6 cents above the consensus estimate and eight cents increased 12 months over 12 months. Consolidated income of $1.57 billion was 10% increased y/y and higher than the $1.52 billion consensus estimate.
The corporate raised its full-year adjusted EPS steering to a spread of 90 cents to $1.10, an 18% enhance from its earlier outlook (on the midpoints). The 2026 consensus estimate was 96 cents on the time of the print. (The corporate reported full-year 2025 adjusted EPS of 63 cents.)
“The optimistic impression of non-compliant capability exiting the market has been realized extra rapidly than initially anticipated, and we stay assured that the enterprise will proceed to ship robust working leverage,” stated President and CEO Jim Filter.
Truckload income elevated 1% y/y to $628 million as a 5% enhance in income per truck was partially offset by a 4% decline in common vans in service. The corporate stated the decrease tractor rely was largely as a result of a tighter driver hiring market. Nevertheless, improved asset utilization is offsetting the decrease truck rely.
The one-way fleet recorded a 16% y/y enhance in income per truck per week, with devoted reporting a 1% enhance.
It flagged the loss of a big devoted buyer, which might be a headwind within the third quarter. This has been accounted for within the firm’s steering. It offered devoted service on 500 new vans within the first half of the 12 months. It stated new devoted contracts will backfill a few of the open vans from the shopper departure, however it might additionally transfer some items over to the one-way fleet to benefit from the spot market.
The TL unit reported a 91.8% working ratio (inverse of working margin), which was 180 foundation factors higher y/y.
Intermodal income slid 1% y/y to $262 million. Income per load was down 2% as size of haul declined. It stated the unit has been getting low-single-digit fee will increase, however newer contract renewals are garnering mid-single-digit will increase. Discovering drayage drivers is getting tougher, however Schneider isn’t including third-party operators to chase quantity.
The intermodal unit reported a 93% OR, 90 bps higher y/y.
Logistics income elevated 11% y/y to $376 million. The unit booked a 96.8% OR, 90 bps higher y/y.
Internet debt leverage ended the quarter at 0.2x, down from 0.3x on the finish of 2025. Schneider lowered its full-year web capex plan to a spread of $350 million to $400 million as it would buy fewer trailers than beforehand deliberate. Internet capex totaled $289 million in 2025.
Why it issues? Schneider Nationwide’s outcomes function a bellwether for the well being of the truckload and intermodal markets. Its commentary on fee restoration and capability administration offers a benchmark for different asset-based carriers.
Extra BigRig articles by Todd Maiden:
- Saia’s Q3 margin steering disappoints buyers
- XPO’s Q2 earnings beat expectations behind robust LTL efficiency
- ArcBest’s Q2 a step on path to restoration
The submit Schneider Nationwide pushes worth amid market imbalance appeared first on BigRig.