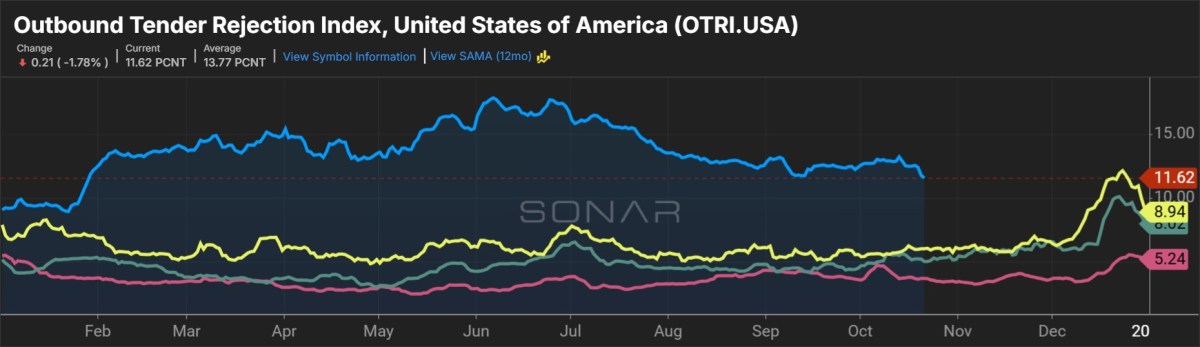
Knight-Swift Transportation is benefitting from its excessive publicity to one-way truckload, the portion of the market experiencing the biggest features from the regulatory-fueled capability shakeout. The provider mentioned Wednesday, along side its better-than-expected third-quarter report, that its tender rejections and spot charges are properly forward of business averages, which is permitting it to rapidly restore margins.
“On the pricing entrance, our spot pricing trended higher than public indicators within the quarter, staying properly above contractual charges that continued to speed up all through the interval,” mentioned CEO Adam Miller in a information launch. “Equally, our tender rejection charges proceed to run at ranges two to a few instances that of the broader market measures.”
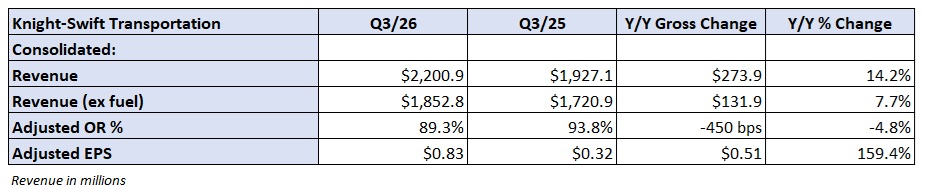
Knight-Swift (NYSE: KNX) reported third-quarter adjusted earnings per share of 83 cents Wednesday after the market closed. The consequence was 51 cents greater than the year-ago quarter and seven cents higher than analysts’ expectations. (Administration’s EPS steering vary was 71 to 77 cents.)
Income of $2.2 billion was up 14% 12 months over 12 months (plus-8% y/y excluding gasoline surcharges) and barely forward of the $2.17 billion consensus estimate.
TL margins flip the nook
The corporate’s TL unit reported a 6.5% y/y income improve, excluding gasoline. Income per tractor (ex-fuel) was up 11% y/y whereas the common tractor depend was down 4%.
Knight-Swift has been culling its truck fleet by way of the downturn to enhance asset utilization. Loaded miles per tractor elevated 1%, which was an eighth straight y/y enchancment. Deadhead was down 170 foundation factors y/y to 12.1%. Income per loaded mile (ex-fuel) elevated 10% y/y. (The metric was up by a mid-teen share in its over-the-road service.)
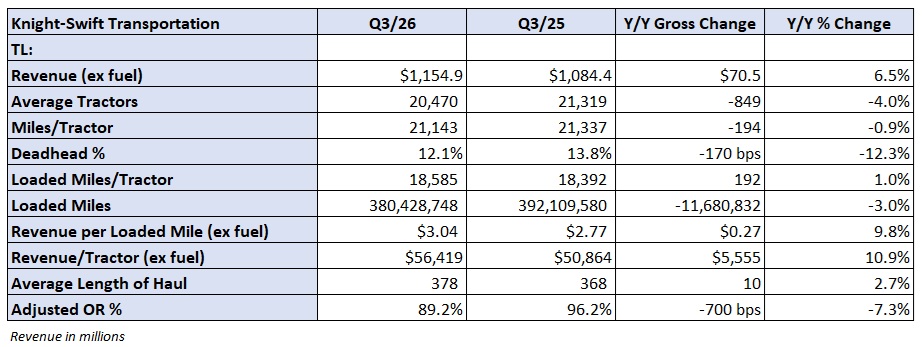
An 89.2% adjusted working ratio (inverse of working margin) was 700 bps higher y/y and in keeping with the midpoint of administration’s steering vary. U.S. Xpress, which was acquired in 2023, operated at a low-90% adjusted OR within the quarter whereas Knight-Swift’s legacy manufacturers operated at 88%. Administration famous that one-way margins exceeded devoted margins within the interval. (Roughly 29% of Knight-Swift’s TL fleet operates underneath devoted contracts.)
The provider is meaningfully pricing freight above price inflation. Through the first quarter, a rise in income per whole mile (ex-fuel) lagged the rise in price per mile (internet of gasoline surcharges) by 90 bps. The unfold flipped to 390 bps optimistic within the second quarter, with price features outpacing price inflation by 840 bps within the third quarter.
The corporate is once more calling for 650 to 750 bps of y/y TL margin enchancment within the fourth quarter, implying an 85.9% adjusted OR (330 bps higher sequentially). Its steering additionally requires income to extend y/y by a low-double-digit share (ex-fuel).
It mentioned it is going to look to selectively develop the fleet, however acknowledged “sourcing high quality drivers is as difficult because it has been in years.” Knight-Swift’s new bid season kicks off subsequent month and it’ll ask for “at the least double-digit [rate] will increase” for starters, Miller mentioned on Wednesday night name with analysts.
“I feel we’ll begin the bid season with the concept of in all probability low-to-mid double digits and see the way it develops from there.”
Nationwide LTL map could also be accomplished organically
Knight-Swift entered the less-than-truckload market in 2021 when it acquired AAA Cooper. It added Midwest Motor Specific later that 12 months and Reliable Freeway Specific in 2024. It has added over 50 areas organically over the previous 5 years, together with 4 new areas in Might.
Nonetheless, it nonetheless must fill within the Northeast portion of the map to finish a real nationwide community. It mentioned Wednesday it has already chosen just a few areas within the area and plans so as to add terminals organically at a “very deliberate” tempo.
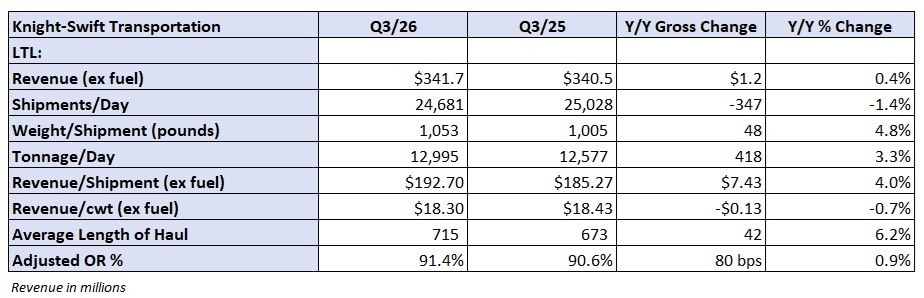
Income within the unit was up lower than 1% y/y (ex-fuel) within the quarter as tonnage elevated 3% and income per hundredweight (ex-fuel) fell 1%. Will increase in weight per cargo (+5%) and size of haul (+6%) had principally offsetting impacts on yield.
Income per cargo (ex-fuel) elevated 4% y/y. Contractual price renewals had been up by a mid-single-digit share.
The LTL unit booked a 91.4% adjusted OR, 80 bps worse y/y. A $4.6-million decline in features on sale was a 130-bp y/y margin headwind.
The corporate’s fourth-quarter outlook requires a high-single- to low-double-digit y/y improve in income (ex-fuel), with 100 to 200 bps of y/y margin enchancment, implying a 93.6% OR on the midpoint of the vary.
Different Q3 takeaways
The logistics unit reported 120 bps of y/y margin enchancment to a 93.1% adjusted OR. Brokerage gross margin elevated 110 bps y/y to 18.9% (350 bps higher sequentially) as the corporate “maintained a disciplined method to profitability and provider choice.”
The intermodal unit booked a second straight working revenue (97.8% adjusted OR). Load counts elevated 13% y/y to the best degree in over 5 years and income per load was 15% greater (up 5.5% y/y ex-fuel).
Knight-Swift issued fourth-quarter adjusted EPS steering of 78 to 84 cents, which bracketed the 82-cent consensus estimate on the time of the print.
The third-quarter adjusted EPS quantity benefitted y/y from a $22-million discount in internet curiosity expense (10 cents per share), a decrease tax price (5 cents per share) and a slight improve in features on gear gross sales (1 cent per share). Nonetheless, the opposite revenue line was down $3.5 million y/y (2 cents per share).
Why it issues? Knight-Swift is the nation’s largest asset-based TL provider and serves as a bellwether for market developments. The corporate’s third-quarter outcomes spotlight that the market has transitioned from a cyclical downturn to a structural restoration.
Extra BigRig articles by Todd Maiden:
- Heartland Specific sees earnings turnaround in Q3
- Werner Enterprises points Q3 revenue warning
- J.B. Hunt experiences rising pains in Q3
The submit Knight-Swift once more eyes large price will increase as new bid season nears appeared first on BigRig.