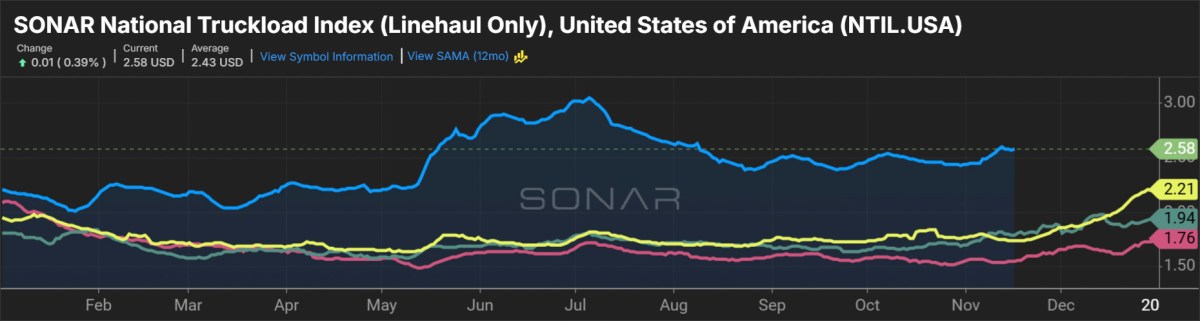
Freight dealer RXO stated Tuesday that regardless that truckload spot charges have cooled within the fourth quarter, the market will not be coming into deflationary territory.
RXO’s (NYSE: RXO) linehaul fee dataset, which excludes gas surcharges, jumped 37.9% yr over yr within the third quarter, to “ranges not seen since peak COVID-era delivery.” To this point within the fourth quarter, fee progress has slowed to plus-26.2% y/y, which is “nonetheless considerably increased than 2025 heading into peak season.”
“In This autumn, the general demand image stays muted towards an unsure financial backdrop, however sustained strain on the provision aspect of the market (carriers) has created a decent setting for shippers — and peak season is quick approaching,” the corporate’s Curve Report said.
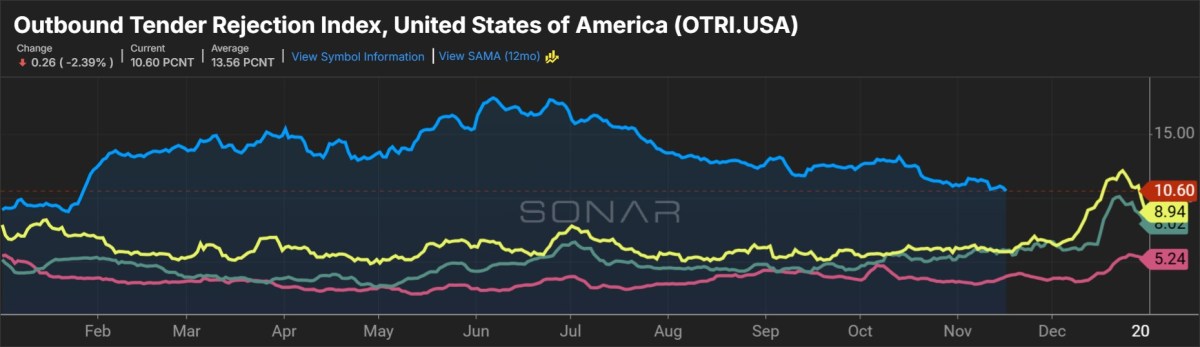
Strict regulatory enforcement and years of weak service profitability have drawn down capability, considerably tightening the market regardless of flat demand.
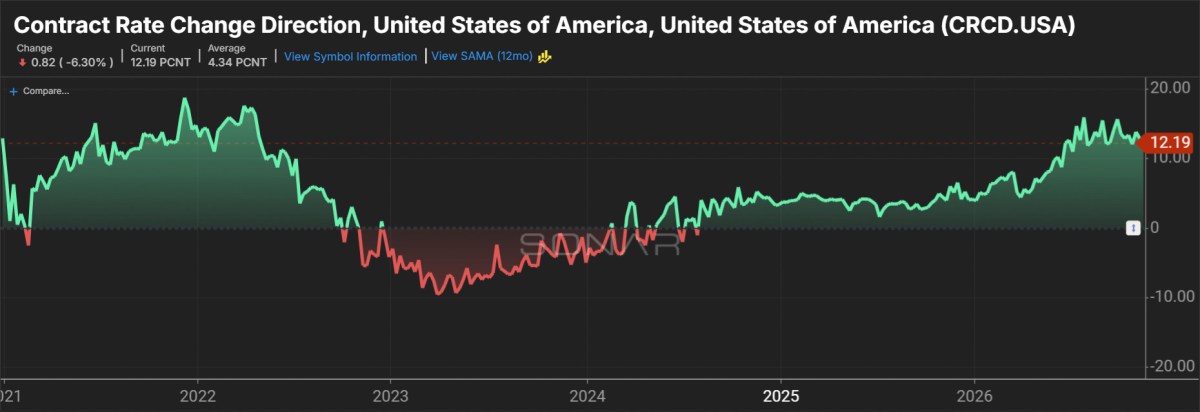
Whereas price pressures dominated the headlines throughout the third-quarter earnings season, fleets are logging massive contractual fee positive aspects after a multiyear downturn. Knight-Swift Transportation (NYSE: KNX) is now concentrating on “at the least double-digit [rate] will increase” in its new bid season, which started earlier this month.
Cass Data Programs (NASDAQ: CASS) stated Monday that linehaul contract charges (ex-fuel) had been up for a twenty second straight month in October, 9.9% increased y/y. The dataset averaged fee will increase of 10% within the third quarter, following a plus-6% common within the second quarter.
“The mixture of federal coverage enforcement, growing insurance coverage premiums, record-high gas, and excessive rates of interest has each lowered the accessible labor pool whereas making the monetary limitations to entry a lot increased,” the RXO report stated. … “So long as freight demand stays muted, there received’t be excessive market volatility, however any incremental improve in shipments might lead to a really troublesome marketplace for shippers.”
RXO’s all-in cost-per-mile index, which incorporates gas surcharges, stood at 160.1 within the third quarter (listed to a 2015 baseline). That is the very best studying for the reason that 2022 first quarter. Diesel gas costs had been up 48% y/y within the quarter, however the report stated diesel didn’t account for all the speed improve.
“A considerably increased price construction has moved the baseline up for carriers, no matter gas prices.”
Why it issues? Pushed by tightening capability and better working prices, these fee tendencies sign a shift in market energy towards carriers searching for margin enchancment. Shippers ought to reply by securing reliable capability and guarding towards routing information deterioration.
Extra BigRig articles by Todd Maiden:
- October TL charges surge as cargo counts prolong constructive streak
- Ahead Air pauses sale of intermodal unit
- Larger cargo weights assist ArcBest beat Q3 expectations
The publish Dealer RXO says TL spot charges not coming into deflationary part appeared first on BigRig.