
A constructive inflection in freight shipments now seems seemingly after 40 months of year-over-year declines, in line with a month-to-month report from Cass Data Methods. A flip in demand would additional bolster the supply-driven fee restoration that started late final 12 months.
The multimodal shipments element of the Cass Freight Index dipped simply 1.2% 12 months over 12 months in Could, the smallest decline in 18 months. Shipments had been up 3% from April however down 0.3% on a seasonally adjusted foundation.
A rise in home intermodal volumes, whereas “many spot indicators recommend bettering freight demand,” drove the change.
“These are constructive indicators {that a} quantity restoration within the second half of the 12 months stays seemingly,” the Monday report mentioned. “Whereas it might not be a consumer-led restoration, inventories are tight, tariffs are falling, and the U.S. greenback is delicate, all of which assist demand progress.”
A 5.2% quantity decline on a two-year-stacked comparability was the smallest since February 2024.
Assuming historic seasonal quantity traits all through the rest of the 12 months, the index is projected to log a 1.8% y/y improve within the again half.
| Could 2026 | y/y | 2-year | m/m | m/m (SA) |
| Shipments | -1.2% | -5.2% | 3.0% | -0.3% |
| Expenditures | 7.5% | 8.3% | 5.3% | 4.9% |
| TL Linehaul Index | 6.9% | 7.5% | 0.4% | NM |
Cass’ expenditures index, which measures whole freight spend together with gasoline, jumped 7.5% y/y and was up 5.3% from April (4.9% larger seasonally adjusted). The y/y improve was the most important since late 2022. A smaller decline in shipments, elevated gasoline costs and better freight charges had been the catalysts for the rise.
Cass’ TL linehaul index, which tracks charges excluding gasoline and accessorial surcharges, elevated 6.9% y/y, the most important improve in almost 4 years. The dataset, which incorporates for-hire spot and contract charges, has been up y/y in 17 consecutive months.
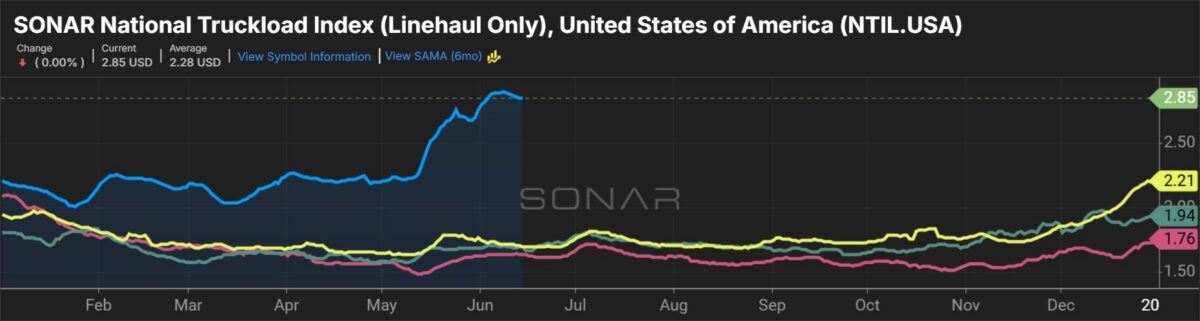
“Volumes are starting to recuperate, however it’s primarily provide constraints supporting larger charges, in our view, each for tools capability and drivers,” the report mentioned.
Truckload capability started to exit final 12 months as authorities tightened enforcement of non-domiciled CDL and English proficiency guidelines, alongside crackdowns on questionable driver colleges and ELD suppliers. Latest occasions (elevated policing of cabotage guidelines and the Supreme Court docket’s dealer legal responsibility ruling) are additional purging noncompliant drivers from the business.
Contract charges set earlier this 12 months are proving too low as capability continues to dwindle, in line with publicly traded carriers showing at an investor convention final week. The group sees the potential for double-digit fee hikes this 12 months and subsequent as routing guides crumble. That may be fairly the turnaround after an almost four-year downturn.
Knowledge used within the indexes comes from freight payments paid by Cass (NASDAQ: CASS), a supplier of fee administration options. Cass processes $37 billion in freight payables yearly on behalf of shoppers.
Extra BigRig articles by Todd Maiden:
- Routing guides are crumbling: ‘It’s completely different this time’
- Truckload carriers eyeing multiyear fee upcycle
- Analysts say Amazon received’t shake LTL market—but
The put up Cass sees freight quantity restoration in second half of 12 months appeared first on BigRig.