
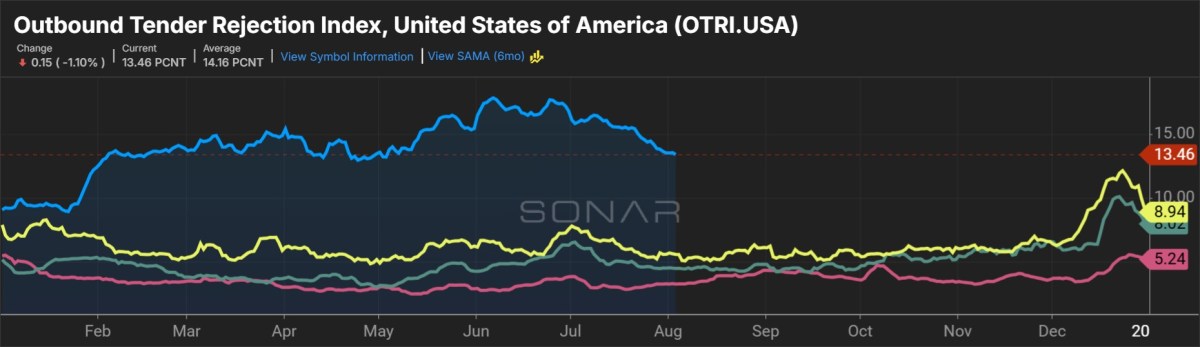
Though the transportation market cooled in July from a seasonally stronger June, it remained very tight, based on information from a month-to-month survey of provide chain professionals. Key transportation metrics within the Logistics Managers’ Index confirmed combined outcomes, with capability falling sooner whereas pricing grew at a barely slower tempo.
The index is a diffusion index during which a studying above 50 signifies growth, whereas one beneath 50 indicators contraction. The LMI displayed a 28.4 studying for transportation capability in July. Sentiment round capability declined at a charge that was 2.4 proportion factors sooner than June, tying the second-fastest contraction charge captured by the 10-year-old dataset. (The record-low studying was 23.8 in September 2020.)
A push by regulatory authorities to take away unsafe drivers has considerably tightened provide within the truckload market. Additional, most publicly traded carriers aren’t including tools, as a substitute making higher use of what they’ve.
Latest initiatives to enhance asset utilization have been obvious in second-quarter outcomes.
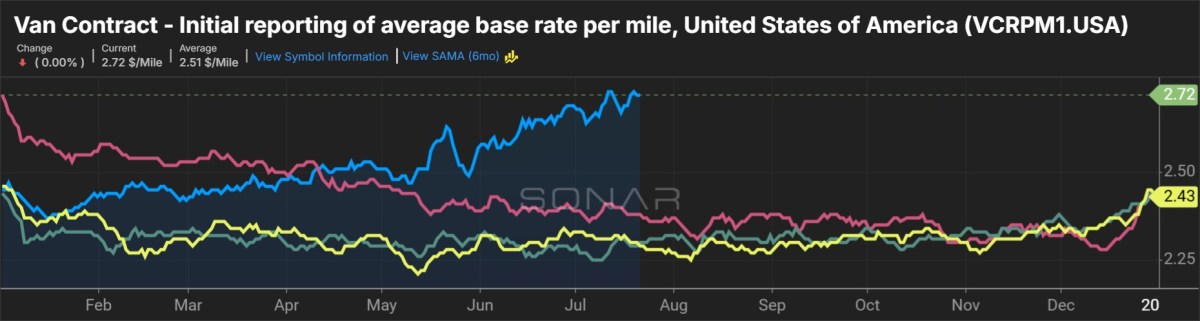
Omaha, Nebraska-based Werner Enterprises (NASDAQ: WERN) introduced an official restructuring of its one-way TL fleet in February. The plan concerned exiting non-profitable accounts and repurposing or disposing under-utilized tractors. Income per truck per week (excluding gasoline surcharges) jumped 28% 12 months over 12 months within the newest quarter, as miles per truck have been up 16% and income per complete mile elevated 10%. It expects charge per mile to extend by 10% to 13% y/y within the third quarter.
The service’s one-way fleet was 34% smaller within the quarter, which helped enhance its complete TL phase adjusted working ratio by 270 foundation factors to 94.5%. Whereas that was roughly 10 factors worse than the prior peak, it was the unit’s greatest margin efficiency because the 2023 fourth quarter.
The Tuesday LMI report confirmed transportation utilization (65) was 9.7 factors decrease than June, however remained elevated by historic requirements. Development in transportation costs (86.9) slowed 5.5 factors however remained at a “very sturdy expansionary charge.”
“The shortage of obtainable fleet capability has precipitated the lead time for tender bookings to extend,” the report said, citing SONAR information. “In late July bookings have been being made at a median of three.74 days earlier than the tender wants to maneuver, up 11% from the identical time final 12 months.”
Werner famous one-way contractual bid negotiations are returning among the strongest will increase in a decade.
Inexperienced Bay, Wisconsin-based Schneider Nationwide’s (NYSE: SNDR) one-way fleet captured double-digit charge will increase on contract renewals within the quarter. It stated mini-bid exercise is up as shippers develop extra involved with securing capability for peak season. Schneider has elevated its publicity to the spot market, noting June carefully resembled March 2021, the prior cycle peak. It believes the TL market is “solely within the early levels of charge restoration.”
Provide chain prices stay elevated
The general LMI (68.9) was down 2.2 factors from a four-year excessive in June. Even with the modest step down, the index is on observe for the very best annual studying because the freight market’s increase cycle in 2021.
Stock ranges (55) have been down 5.5 factors within the month, with downstream firms, like retailers, registering an virtually 20-point decline into contraction territory at 46.3. Upstream respondents (producers and wholesalers) reported little change, returning a studying of 59.
“This appears to assist the speculation laid out final month that among the surge in imports was resulting from retailers speeding some items imports forward of latest potential tariffs,” the report stated. “It’s not clear if there will probably be a repeat of what we noticed final 12 months the place the majority of this stock was held Upstream on the wholesale stage after which solely pulled down proper earlier than the vacation purchasing season.”
Even with the slowdown in stock development, stock prices (77) grew at a “very sturdy charge,” up 1.1 factors from June.
Warehousing capability (46.3) was down 1.2 factors, pushing warehouse costs (75.5) up 1.7 factors to the second-highest studying since July 2022, “the peak of the post-covid stock bullwhip.”
The readings confirmed a a lot tighter warehousing marketplace for upstream firms. Warehouse costs have been 12 factors larger on the wholesale stage of the availability chain.
Combination logistics prices (stock, warehousing and transportation) have been down 2.6 factors to 239.5 in July. Could’s 250.9 studying marked the quickest charge of growth for the all-in price dataset since March 2022.
Logistics managers surveyed anticipate the transportation market to stay very tight over the following 12 months, returning future readings of 40.4 for capability, 71.8 for utilization and 89.2 for pricing.
The outlook pegged stock ranges at 64.4 one 12 months out, with stock prices (77.6) and warehouse costs (76.3) displaying no retreat.
“Basically, respondents are anticipating having to suit rising inventories into tighter capacities at larger prices over the following 12 months.”
The LMI is a collaboration amongst Arizona State College, Colorado State College, Florida Atlantic College, Rutgers College and the College of Nevada, Reno, carried out with the Council of Provide Chain Administration Professionals.
Why it issues? The Logistics Managers’ Index offers a have a look at all main provide chain price buckets. The newest report indicators a tough working setting for shippers characterised by tight capability and rising price pressures.
Extra BigRig articles by Todd Maiden:
- July’s 55.6% PMI highest in 4 years; LTL carriers getting bullish
- Schneider Nationwide pushes worth amid market imbalance
- Saia’s Q3 margin steering disappoints traders
The submit Transportation capability falls sooner in July, charges stay excessive appeared first on BigRig.