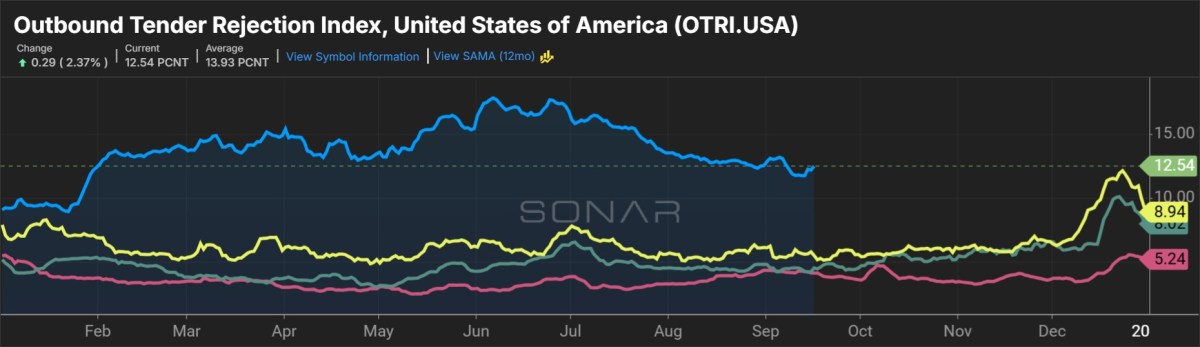
The truckload capability correction continues to be within the “early innings,” provider executives stated at an investor convention this week.
A regulatory crackdown launched a yr in the past compounded the impression of extended financial weak point, which had already compelled quite a few small and midsize fleets out of the trade. The current surge in diesel gas costs has additional plagued small operators, a lot of whom don’t have restoration mechanisms in place. Additionally, the Supreme Court docket’s dealer legal responsibility ruling provides one other gating issue on capability, requiring each brokers and shippers to extra rigorously choose their transportation companions.
“There was no normal for entry-level driver coaching,” Jim Filter, Schneider Nationwide (NYSE: SNDR) President and CEO, stated at Morgan Stanley’s Annual Laguna Convention.
He pointed to the hundreds of drivers who joined the trade throughout the earlier upcycle, noting that many acquired their authority unlawfully and lacked correct coaching. The entry level for this group has been narrowed, with the compelled closure of sham driver colleges. The capability that’s coming into the market is being scrutinized extra closely than up to now as shippers and brokers are much less prone to tender masses to new motor carriers with out security rankings. Additional, strict oversight of ELD suppliers is protecting drivers from skirting hours-of-service guidelines.
These actions are persevering with to take away the drivers that “weren’t enjoying by the identical guidelines as everyone else,” Filter stated.
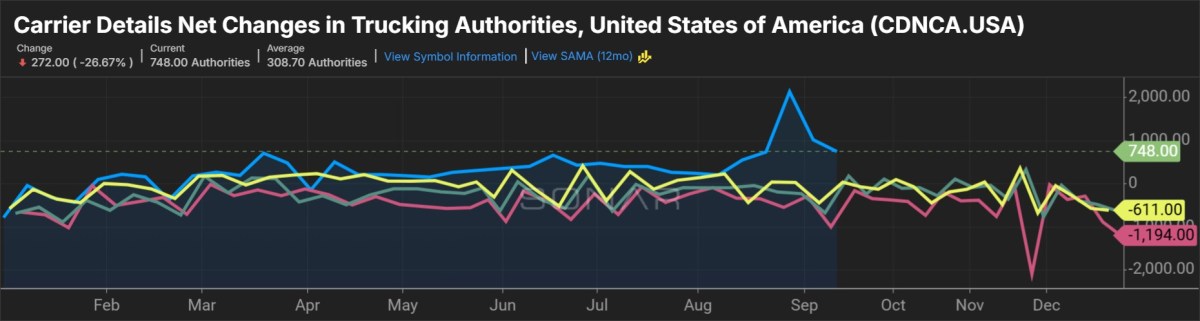
Executives from Werner Enterprises (NASDAQ: WERN) echoed the impacts the adjustments are having on provider choice. They imagine that the trade’s capability crunch might solely be within the second or third inning, noting the screws have additional tightened following the dealer legal responsibility (Montgomery) ruling.
Werner’s administration staff cited a current Texas Supreme Court docket ruling involving Residence Depot (NYSE: HD). In that case, the retailer was dismissed as a defendant in a legal responsibility go well with over a deadly accident that occurred whereas Werner was transporting its cargo. In the end, the courtroom decided that Residence Depot met its authorized obligation just by hiring a good provider.
Filter stated Schneider’s brokerage unit has culled its accepted provider listing to only 14,000 from 60,000 on the peak. The corporate initially began eradicating operators a few years in the past in efforts to thwart cargo theft.
“I can inform you that there aren’t 100,000 carriers on the market that I feel any of us would have the ability to have a look at and say, 100,000 carriers are secure and needs to be on the market on the highway,” Filter stated.
Whereas the mud continues to be settling after the Montgomery resolution, he believes a big phase of carriers gained’t have the ability to qualify for legal responsibility insurance coverage, or the prices will turn into prohibitive.
Werner stated the capability shakeup has created a possibility to transform personal fleets into devoted clients as obstacles to asset possession have intensified.
Driver availability points have resurfaced and personal fleets don’t have devoted groups to recruit and practice. Many personal fleets expanded throughout the pandemic and at the moment are going through their largest substitute cycle ever amid a high-cost tools surroundings. Additionally, they’ve seen insurance coverage prices proceed to rise and now should ponder self-insurance as a way of managing legal responsibility threat.
Capability, not demand, the larger hurdle to progress?
Schneider is seeing secure demand with some pockets of energy. Minibid exercise has continued as shippers “need to be certain that that they will be protected of their most necessary season.” Nonetheless, Schneider stated demand is just not the largest hurdle to progress—it’s capability.
“Properly, with the quantity of provide that has exited, it has created sufficient demand for our companies,” Filter stated. “We don’t essentially want extra demand.”
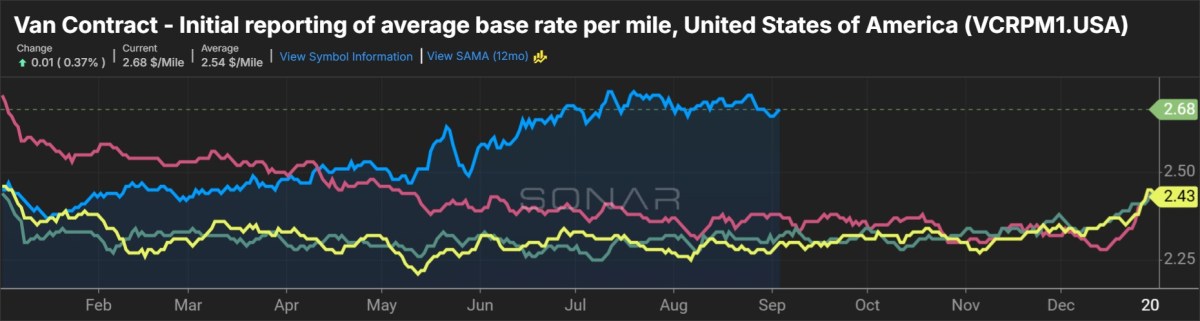
Werner stated demand amongst its largely discount-retail and food-and-beverage buyer base has remained regular from the second quarter to the third quarter. It’s seeing elevated minibid exercise in its one-way phase and curiosity for its devoted companies has spiked.
Werner’s outlook requires a ten% to 13% year-over-year enhance in one-way fee per whole mile throughout the third quarter. The metric was 10% greater y/y within the second quarter, with fleet utilization bettering 16% y/y.
The devoted fleet (80% of its TL community) is forecast to seize a 3% to five% y/y enhance in income per truck per week for full-year 2026. The metric was up 5% y/y within the second quarter, and eight% greater, excluding FirstFleet, which it acquired in January. The devoted phase has been attaining low- to mid-single-digit contractual fee will increase in current months.
Werner cited the potential for “robust” contract fee will increase within the upcoming 2027 bid season, which will get underway within the subsequent 30 to 60 days. It’ll enter contract negotiations throughout peak season when provide tightness can be amplified.
Why it issues? Service choices are dwindling as strict regulatory enforcement and hovering gas costs constrict capability. Consequently, shippers are navigating rising transportation prices, elevated reliance on devoted fleets and heightened competitors to safe capability for peak season.
Extra BigRig articles by Todd Maiden:
- J.B. Hunt flags Q3 price pressures, shares sink 12%
- FedEx Freight expands CTO’s position to cowl business technique following CCO ouster
- Cass: TL charges soar 11% in August, freight shipments flip optimistic
The put up Truckload carriers: Capability exodus rising, not slowing appeared first on BigRig.