Schneider Nationwide introduced Thursday it has inked a deal to make the most of Norfolk Southern’s rail community within the East. The announcement was along with the multimodal transportation supplier’s third-quarter report, which was barely worse than anticipated.
New Norfolk Southern service settlement
Schneider mentioned its new service settlement with Norfolk Southern (NYSE: NSC) will make the corporate the one totally asset-based supplier on a single-line transcontinental railroad within the U.S., assuming the railroad’s merger with peer Union Pacific (NYSE: UNP) is accredited. (Schneider transferred its Western intermodal enterprise to Union Pacific in 2023.)
Schneider’s intermodal service is executed with its personal drivers and tractors, chassis (23,900), containers (26,800) and over 60 rail hubs in North America.
“As we transition our main japanese rail supplier to Norfolk Southern, we’ll broaden entry to key markets, improve community flexibility and create new alternatives to higher serve our clients,” mentioned Michael Baumgardt, govt vice chairman of intermodal and logistics at Schneider. “It should strengthen Schneider’s aggressive place and improve the dependable service expertise our clients anticipate.”
The brand new service begins in January.
Schneider pointed to the success it has had with CPKC’s (NYSE: CP) cross-border, steel-wheel service as a think about its resolution to modify suppliers. Schneider mentioned the transfer doesn’t jeopardize its present relationship with CPKC. Schneider was an early consumer of the Southeast Mexico Categorical (SMX), a joint providing from CSX (NASDAQ: CSX) and CPKC, connecting Mexico to Texas and to the Southeast U.S.
“I imply, should you have a look at the UP in the present day, we’re utilizing the CPKC out of Mexico, even supposing they’ve a service,” mentioned Jim Filter, Schneider president and CEO, on a name with analysts. “And so they proceed to function with us and love the whole lot that we’re doing with them, however they perceive there’s a spot that we don’t use them. And so, it’s not that uncommon that you simply’re not going to go along with one supplier for the whole lot.”
Noisy Q3 on path to restoration
Schneider (NYSE: SNDR) reported adjusted earnings per share of 29 cents for the third quarter, a penny under consensus however 17 cents larger yr over yr. Internet curiosity expense was a 5-cent y/y tailwind, partly because of a reversal of curiosity accruals tied to a declare settlement (3 cents). A decrease tax price additionally helped barely. However a separate declare in its logistics section partially offset these advantages.
Consolidated income of $1.59 billion was 9% larger y/y and barely higher than the $1.58-billion consensus estimate.
It raised the underside finish of its full-year adjusted EPS steerage vary by 10 cents to a brand new vary of $1 to $1.10. The consensus estimate was $1.06 on the time of the print. (The corporate reported full-year 2025 adjusted EPS of 63 cents.)
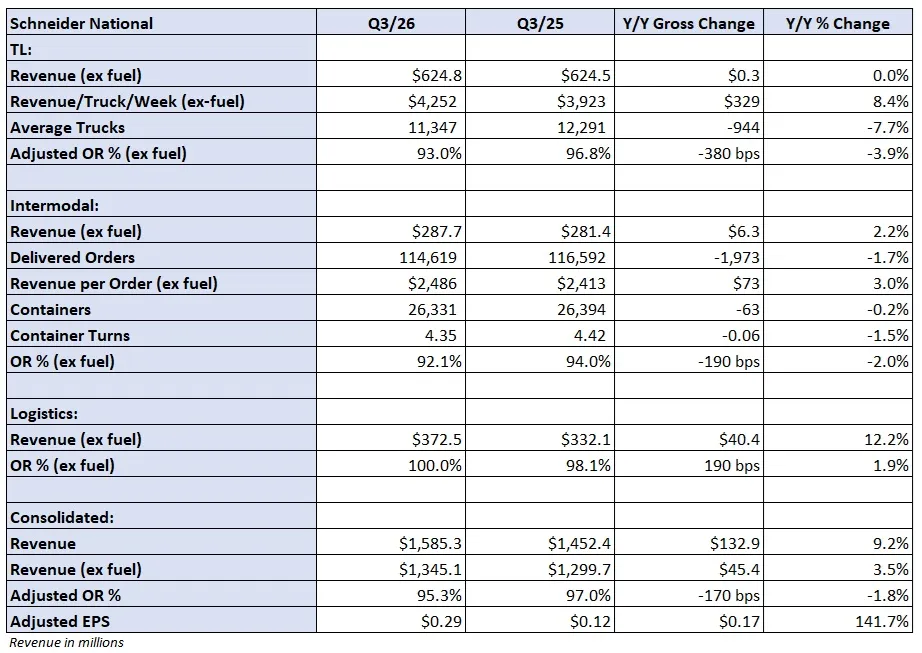
Truckload income (ex-fuel) was flat y/y at $625 million as an 8% improve in income per truck (ex-fuel) was offset by an 8% decline in common vehicles in service. The utilization metric was 3% larger y/y for its devoted fleet and 21% larger for the one-way fleet.
One-way contract renewals averaged slightly below 20% within the quarter, as administration mentioned that the capability crackdown is increasing. This allowed the fleet to return to profitability.
The corporate has bought devoted service on 850 vehicles this yr, however continues to be working to offset a beforehand disclosed buyer loss.
The TL unit reported a 93% working ratio (inverse of working margin), which was 380 foundation factors higher y/y, however 120 bps worse than the second quarter.
Intermodal income (ex-fuel) elevated 2% y/y to $288 million. A 2% decline in masses was offset by a 3% improve in income per load (ex-fuel). Intermodal contract renewals are “comfortably within the mid-single-digit vary,” administration mentioned. The unit reported a 92.1% OR, 190 bps higher y/y.
The logistics section reported breakeven outcomes as a confidential declare settlement negatively impacted the interval.
Internet debt leverage was 0.1x on the finish of the quarter, down from 0.3x on the finish of 2025. Schneider lowered its full-year internet capex plan to a spread of $325 million to $350 million. Internet capex totaled $289 million in 2025.
Why it issues? Schneider’s new service settlement with Norfolk Southern expands its market entry and probably establishes it as a novel asset-based supplier on a single-line transcontinental rail community alongside its rising cross-border intermodal service. In the meantime, Schneider’s outcomes function a bellwether for the well being of the truckload and intermodal markets.
Extra BigRig articles by Todd Maiden:
- FedEx Freight sees volumes stabilize, eyes This fall margin enchancment
- Saia’s expanded terminal community delivers report income, tonnage
- XPO’s pricing, working initiatives drive Q3 beat
The submit Schneider companions with Norfolk Southern; raises outlook regardless of Q3 miss appeared first on BigRig.