
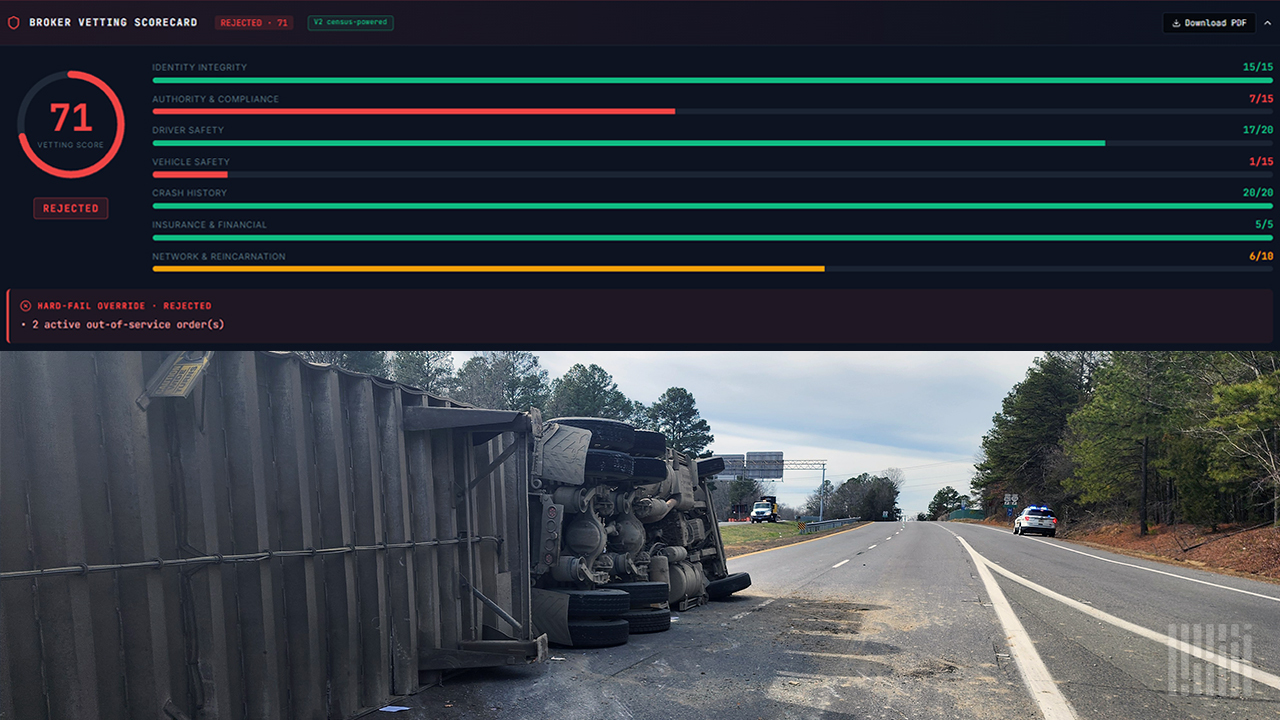
Because the Supreme Court docket handed down Montgomery v. Caribe Transport on Could 14, I’ve not been capable of get via a cellphone name, a deposition prep, or a LinkedIn thread with out any person asking me the identical query. What makes a provider secure? If we can’t simply lean on FMCSA’s SAFER snapshot anymore, what’s the goal customary?
I perceive why everyone is asking it. It’s the incorrect query.
Right here is the short refresher, as a result of the remainder of this depends upon it. The justices dominated 9 to 0. Justice Amy Coney Barrett wrote the opinion, and Justice Brett Kavanaugh filed a concurrence joined by Justice Samuel Alito. The plaintiff, Shawn Montgomery, misplaced a part of his leg in 2017 when a Caribe Transport truck struck his parked tractor-trailer on an Illinois shoulder. C.H. Robinson brokered the load. Caribe carried a conditional security score on the time. The Court docket held that the Federal Aviation Administration Authorization Act doesn’t preempt a negligent choice declare in opposition to the dealer, as a result of the statute’s security exception saves it. For roughly a decade, brokers leaned on FAAAA preemption to get these circumstances dismissed earlier than discovery ever began. That protect is gone.
And the reasoning doesn’t cease at licensed brokers. The precept the Court docket introduced is that exercising atypical care when you choose a provider issues motorized vehicle security. That logic reaches shippers who choose carriers straight, third-party logistics suppliers, and digital freight platforms. Anyone within the chain who selects a provider and who has entry to the general public security information is now uncovered.
Three phrases that aren’t synonyms
Virtually each dialog I’ve about this runs aground on the identical downside. Protected, compliant, and dangerous are three totally different phrases, but the trade makes use of them as in the event that they imply the identical factor. They don’t.
Compliant means a provider meets the minimal customary the federal authorities will settle for earlier than it lets that provider hold its working authority. Compliance is a flooring. It’s pass-or-fail, and the bar is ready low on objective as a result of the Federal Motor Provider Security Rules are a nationwide minimal, not a greatest follow. When a provider is compliant, what you really know is that, on the day somebody checked, it was not thus far out of line that the federal government would withdraw its authority. That’s the entire assure.
Protected describes an operational final result. Did the truck get from level A to level B with out hurting anybody or damaging the freight? Protected is a backward-looking observe file, principally a perform of issues laborious to see from the skin.
Danger is the one nearly no one defines, and it’s the one which issues. Danger is publicity. It’s the quantity of monetary and human harm a provider is able to inflicting, the probability it’s going to trigger it, and the query of who pays when it does. Danger is forward-looking, probabilistic, and encompasses a whole class of things unrelated to security or compliance.
Right here is the half folks miss. A provider may be compliant and unsafe. A provider may be secure and out of compliance on paper. A provider may be each secure and compliant and nonetheless be a genuinely dangerous danger. After Montgomery, when that provider causes a catastrophic crash, safe-and-compliant shouldn’t be the protect folks suppose it’s, as a result of the plaintiff’s lawyer shouldn’t be going to argue compliance. He’s going to argue danger, and that you might have seen it coming.
Danger 101: frequency and severity
When you’ve got ever sat throughout the desk from an underwriter, you already understand how they suppose. Danger has two axes. Frequency and severity. How usually one thing dangerous occurs, and the way dangerous it’s when it does. Multiply them and also you get anticipated loss, the actuarial backbone of each business auto premium ever written.
Now discover what shouldn’t be in that equation. There isn’t any line merchandise for security score. There isn’t any subject for compliant, sure or no. These issues would possibly correlate loosely with frequency. They inform you nearly nothing about severity, and severity is the place firms die.
When an insurer retains me to evaluate a fleet, I’m not grading the fleet’s character. I’m estimating frequency, estimating severity, and pricing publicity. Provider vetting, executed appropriately, is the very same lens utilized to a hiring determination fairly than a coverage.
The FMCSA information entice
So allow us to discuss in regards to the information the trade really leans on. FMCSA assigns precisely three security rankings, and solely after an on-site compliance evaluate. Passable, Conditional, Unsatisfactory. That’s the whole scale.
Right here is the quantity that ought to reframe the dialog. Roughly 92 p.c of carriers haven’t any score in any respect. They’re Unrated. Out of one thing like 780,000 motor carriers, the overwhelming majority have by no means had an auditor stroll via the door.
So when a dealer or a shipper pulls up a provider and the score subject says Unrated, that doesn’t imply secure. It means no one from the federal authorities has appeared. The absence of a foul score will get learn as a very good score. It’s not one. Unrated shouldn’t be a clear invoice of well being. It’s an empty file.
Passable has its personal downside: time. A passable score may be six, eight, or ten years outdated, indicating an organization which will now not be functioning. Conditional, the score that does carry weight, carries it within the incorrect path. It means FMCSA has already discovered severe deficiencies. That was the precise reality sample in Montgomery. Caribe carried a conditional score. That isn’t a coincidence on this case. That’s the case.
SAFER is a skinny, lagging, principally empty dataset that was by no means constructed to measure publicity. It was constructed to assist FMCSA triage which carriers to analyze. The trade borrowed it as a hiring software as a result of it was free and accessible. Free and there may be not the identical as sufficient.
What really goes right into a danger profile
If FMCSA information is a skinny slice, what’s the entire image? An actual 360-degree provider danger profile goes nicely previous SAFER.
It begins with monetary well being, as a result of a provider underneath monetary stress makes predictable selections. It defers upkeep, stretches commerce cycles, cancels the telematics, and lets the protection director’s seat sit empty. None of that reveals up as a violation till after it reveals up as a crash. It consists of tradition, as OSHA historical past will inform you, as a result of how an organization runs its store tells you the way it runs all the things else. It consists of company construction, the shared officers and addresses and recycled authorities that expose a chameleon provider, the operation that lets a foul authority die and reincarnates clear underneath a recent DOT quantity. It consists of federal litigation historical past, one of many loudest danger indicators there may be and one nearly no one reads earlier than tendering a load. It consists of catastrophic publicity and the PHMSA incident historical past, which captures the low-frequency, high-severity tail danger that ends firms.
Virtually none of that’s compliance information. Most of it’s not security information. It’s danger information and public. The rationale most provider vetting doesn’t appear like that is that only a few folks on this trade have really sat within the loss management chair.
That’s the reason my companion and I constructed Tea Applied sciences and the CarrierVerifi platform to consolidate that work: doing it by hand throughout a dozen separate public methods for each provider you contact shouldn’t be reasonable, and never reasonable shouldn’t be a protection a jury will settle for anymore.
The vetting course of briefly
If security rankings aren’t the usual, what’s the precise course of? Give it some thought in three phases.
Earlier than you tender, run an actual pre-tender display. Affirm lively authority via dwell FMCSA information, not a quantity any person emailed you, and match the MC and DOT numbers, authorized title, cellphone and e mail area to catch double-brokering and identification theft. Deal with authority underneath 12 to 18 months as a motive to look more durable, not a motive to look away. Confirm insurance coverage correctly, present, in drive, limits that really match the publicity, and get the certificates from the agent, not the provider. Learn the FMCSA information appropriately, weighting a excessive Unsafe Driving percentile otherwise than a paperwork class, and weighting a deadly crash otherwise than a tow-away. Then go previous FMCSA into the monetary, company, litigation and PHMSA image.
Make the method itself defensible. Have a written provider vetting SOP, observe it the identical manner each time, and doc that you just did. In discovery, the very first thing a plaintiff’s lawyer requests is your vetting coverage and the file on the provider that crashed. An undocumented course of and a nonexistent one look equivalent to a jury.
Monitor constantly, as a result of a danger profile is a movie, not {a photograph}. The provider you vetted in January can have lapsed protection, three new crashes and a downgraded score by June. Observe trajectory, not simply absolute scores. A provider whose violations are climbing poses a unique danger than one trending down.
This carries all the way down to the motive force stage, too, the place compliance is once more only a flooring. A once-a-year MVR pull is compliant, however it means a February DUI stays invisible till the next January. A highway take a look at shouldn’t be federally required, however for those who skip it, the query earlier than the jury turns into whether or not ten minutes of driving down the highway to verify {that a} driver might function the truck was an excessive amount of to ask to maintain somebody alive. The hole between the minimal and the defensible customary is the whole level.
The insurance coverage blind spot
There may be one piece nearly no one places in a danger profile, and it might be the most costly omission of all. Insurance coverage itself.
Freight brokers aren’t federally required to hold legal responsibility insurance coverage. What a dealer should have is a $75,000 surety bond, the BMC-84, which exists to make sure carriers and shippers receives a commission, to not cowl a wrongful-death verdict. Kavanaugh flagged precisely this hole in his Montgomery concurrence. A big share of the brokerage world is mom-and-pop, single-member LLC operations with no workplace, no property and no legal responsibility coverage. Montgomery made these brokers liable. It didn’t make them collectible. When the named defendant has nothing, the publicity travels up the chain to whoever does have protection and property, which more and more means the shipper.
Even amongst firms that do carry insurance coverage, a coverage shouldn’t be the identical as safety. Two issues go incorrect. Limits, as a result of catastrophic verdicts land above coverage limits and any person absorbs the surplus. Language, the exclusions, and sublimits are buried within the doc. I labored on a cargo loss on a 1.5 million greenback piece of oilfield tools that got here off an open-deck flatbed. A one-million-dollar cargo coverage was in place. It appeared sufficient. It was not. The coverage restricted open-deck cargo harm to 150,000 {dollars}, and the shipper absorbed the remaining. No one learn the open-deck language till the declare was filed.
Insurance coverage belongs in a danger profile, however not as a yes-or-no subject. The actual questions are what the boundaries are in opposition to the reasonable severity of a loss, and what the language does when a declare is definitely filed.
The correct query
So when the trade retains asking what makes a provider secure, I might push again. Protected is a backward-looking final result; compliant is a minimal flooring; neither tells you what you could know earlier than you set a provider on the highway along with your title connected to the load.
The query that does the work is that this. What is that this provider’s danger profile, and the way a lot publicity does it carry, to the motoring public, to its insurer, and now, after Montgomery, to the dealer and shipper who chosen it. And the companion query a deposition will ultimately ask you straight: how good is your individual course of for vetting, qualifying and screening carriers, and would it not survive a day of cross-examination.
I get to be on tv and write columns, and I worth that. However the day job beneath it’s this. I’m an skilled witness in business motorized vehicle litigation and a loss and danger management advisor to insurers, underwriters and the attorneys who strive these circumstances. They taught me a very long time in the past that danger, not security and never compliance, is the place this entire factor really lives.
Protected shouldn’t be at all times exposure-free. Compliance shouldn’t be at all times secure. What “security” means doesn’t matter. Danger is the one one of many three that decides who pays.
I’ve printed an extended working primer that walks via the complete three-phase vetting course of, the driver-level program, and the 120-question danger management evaluation we use within the subject right here.
The submit Provider vetting 101. Spoiler: It’s not about security. appeared first on BigRig.