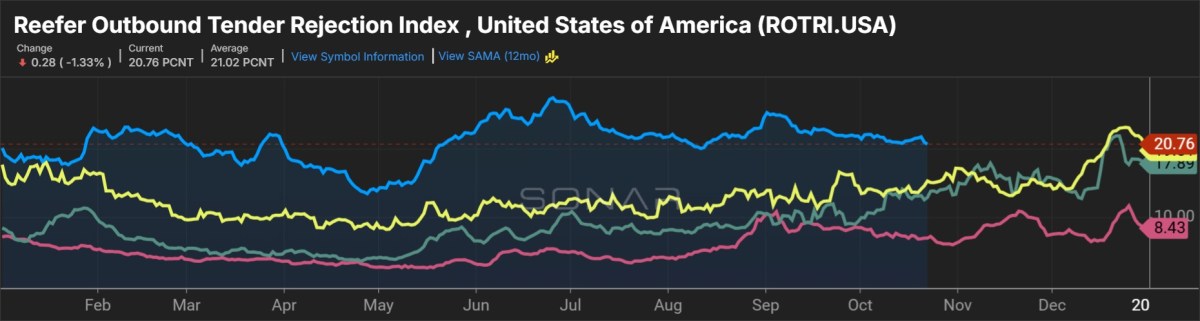
Shares of refrigerated service Marten Transport had been down 7% in noon buying and selling on Friday, following a disappointing third-quarter report. Regardless of enhancing supply-demand fundamentals, a runup in gas and medical insurance prices, amongst different objects, had been a drag within the interval.
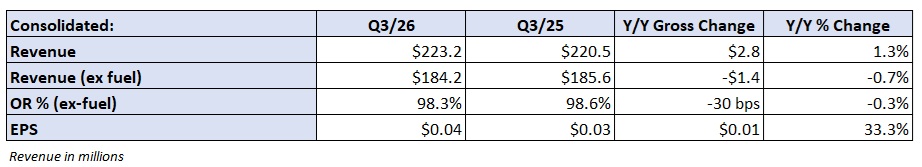
Mondovi, Wisconsin-based Marten (NASDAQ: MRTN) reported internet earnings of $2.9 million, or 4 cents per share, for the third quarter. The outcome was a penny increased than the year-ago quarter however 2 cents mild of the consensus estimate.
The corporate stated increased gas and wages and advantages prices, together with driver pay will increase, had been solely partially offset by a rise in positive aspects on tools gross sales. The web impression was $3.7-million hit to internet earnings, or 4.5 cents per share.
Consolidated income of $223 million was 1% increased 12 months over 12 months. The 2025 sale of its intermodal unit to Hub Group (NASDAQ: HUBG) introduced a $9.9-million income headwind in the course of the quarter.
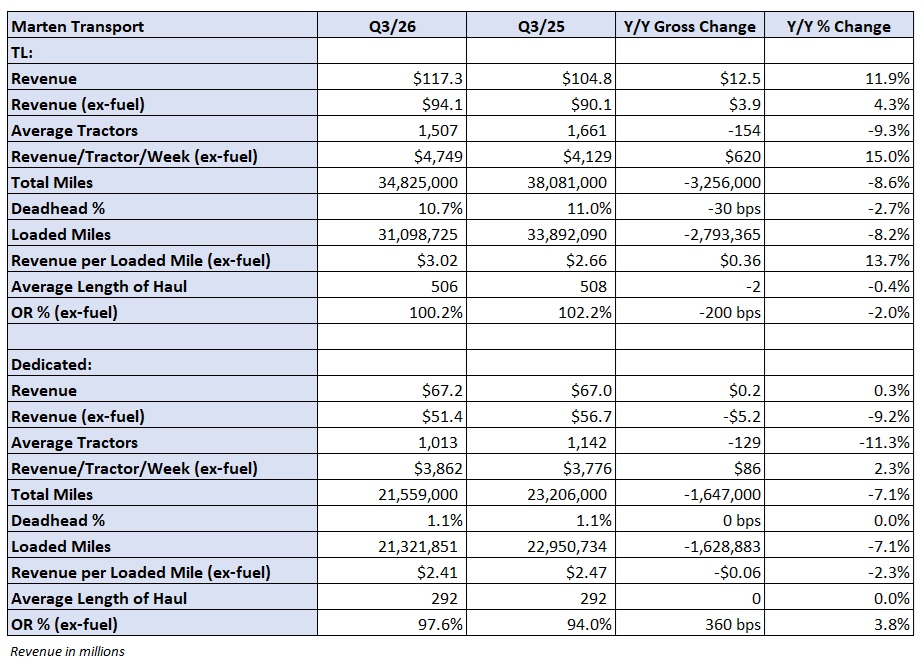
One-way truckload income elevated 12% y/y to $117 million. Excluding gas surcharges, income was up 4% y/y as income per tractor per week (ex-fuel) elevated 15% on a 9% smaller fleet.
Marten has been managing truck counts to enhance asset utilization. Deadhead was down 30 foundation factors y/y to 10.7%. Income per loaded mile (ex-fuel) elevated 14% y/y to $3.02. The unit was unprofitable at a 100.2% working ratio (ex-fuel), 200 bps higher y/y, however 280 bps worse sequentially.
The devoted section reported a 9% y/y decline in income (ex-fuel) as an 11% decline within the truck depend was solely partially offset by a 2% enhance in income per tractor (ex-fuel). Income per loaded mile (ex-fuel) was down 2% y/y to $2.41. The unit logged a 97.6% OR (ex-fuel), 360 bps worse y/y and 220 bps worse sequentially.
(Marten doesn’t host a quarterly name.)
“The truckload freight market has sharply tightened since earlier this 12 months as renewed and enhanced enforcement of federal and state regulation is eradicating a significant quantity of noncompliant and unqualified driver capability from {the marketplace},” stated Randy Marten, chairman and CEO, in a information launch. “We’re securing increased pricing from our prospects for our premium companies whereas enhancing freight high quality throughout our community inside these early levels of the freight market upcycle.”
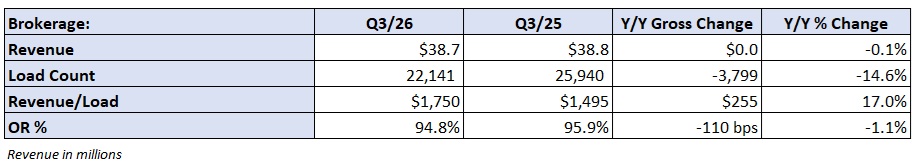
Brokerage income was flat y/y at $39 million as a 15% decline in shipments was offset by a 17% enhance in income per load. The unit’s OR improved 110 bps to 94.8%, flat with the 2026 second quarter.
Money movement from operations was $83 million within the first 9 months of 2026, a 5% y/y decline. The corporate maintained a debt-free stability sheet within the interval.
The typical age of its tractor fleet was 2.5 years in comparison with 2.2 years within the year-ago quarter.
Shares of MRTN are down 37% since a mid-June peak.
Why it issues? Marten Transport is seen as a “refrigerated pure play.” It’s the solely public service within the reefer market and its quarterly outcomes function a bellwether for the trade.
Extra BigRig articles by Todd Maiden:
- Knight-Swift once more eyes huge fee will increase as new bid season nears
- Heartland Specific sees earnings turnaround in Q3
- Werner Enterprises points Q3 revenue warning
The submit Price pressures sink Marten Transport’s Q3 appeared first on BigRig.