
Shares of J.B. Hunt Transport Companies had been down 12% in early Wednesday buying and selling following a third-quarter earnings warning. Firm executives mentioned late Tuesday at an investor convention that near-term price pressures had been outpacing pricing good points, seemingly leading to a 5% to 10% sequential decline in EPS for the present interval. It pointed to a pointy runup in diesel gas costs and driver-related bills as the first culprits.
The replace implies third-quarter EPS of $1.77 on the midpoint of the vary, roughly 16% gentle of the present $2.10 consensus estimate. The consequence can be roughly in step with the 2025 third quarter. It flagged $25 million in incremental driver-related prices (recruiting, bonuses, and so forth.) and a minimum of a $10-million sequential gas headwind.
Gas surcharges function on a one-week lag. Diesel costs had been up 10% sequentially from July to August and have continued to step increased by September. Diesel costs have elevated sequentially in eight of the 11 weeks of the third quarter. The near-term headwind will develop into an earnings tailwind when costs revert.
J.B. Hunt (NASDAQ: JBHT) mentioned Tuesday night at a Morgan Stanley convention that the fee inflation is “extra cyclical than structural,” and that increased driver prices are an indication of a powerful freight market. The corporate additionally seems to be frontloading some prices because it preps for peak season and longer-term development.
Importantly, 96% of J.B. Hunt’s working revenue is generated by its intermodal and devoted models, each of that are gradual to seize price inflections, creating “extra of a timing concern.” Intermodal contract pricing usually lags truckload pricing by two quarters. Its devoted contracts are largely five-year offers with annual cost-based value escalators which can be much less delicate to market swings.
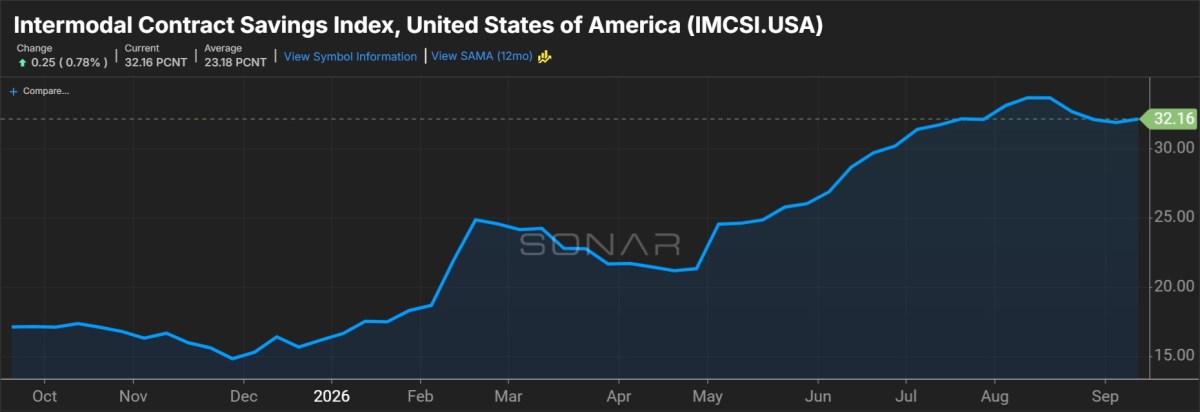
The corporate’s intermodal bid season begins in October, with roughly 10% of its contracts renewing within the fourth quarter. (The remainder of the contracts renew evenly by quarters one by three.) Sonar information exhibits the mode is presently 32% cheaper than truck, which is notably increased than the standard 10% to fifteen% low cost carried within the East (roughly 25% within the West). Administration sees “an enormous alternative to shut that hole” within the upcoming bid season, however mentioned it gained’t implement “out-of-cycle” price hikes to get there. Doing so usually has lingering results on buyer relationships when the market corrects.
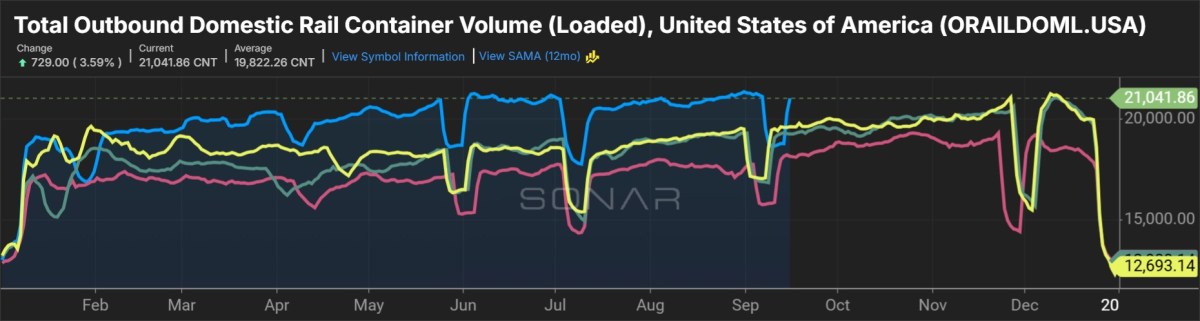
General, it continues to see “actually robust demand” throughout all companies, with final-mile being the outlier. It has been taking market share in intermodal and truckload in latest quarters, however mentioned it’s extra targeted on yield over quantity till margins are restored. Document gas costs and elevated TL charges stay catalysts for road-to-rail conversion. Its devoted pipeline additionally sits at an all-time excessive.
Whereas the 2026 third quarter might snap a streak of 4 consecutive quarters of year-over-year margin and earnings enchancment, the capability state of affairs is “not letting up in any respect, if something it’s in all probability getting worse.” That performs into the arms of scaled asset-based operators.
Why it issues? Whereas different carriers are seemingly experiencing related price headwinds, the affect on J.B. Hunt is exclusive as a result of its deal with intermodal and devoted providers. As a result of these segments modify to price modifications extra slowly than over-the-road operators, near-term margin pressures for different suppliers could also be much less extreme than these confronted by J.B. Hunt.
Extra BigRig articles by Todd Maiden:
- FedEx Freight expands CTO’s function to cowl business technique following CCO ouster
- Cass: TL charges bounce 11% in August, freight shipments flip optimistic
- Hub Group warns of Nasdaq delisting discover; flags H1 working loss
The put up J.B. Hunt flags Q3 price pressures, shares sink 12% appeared first on BigRig.