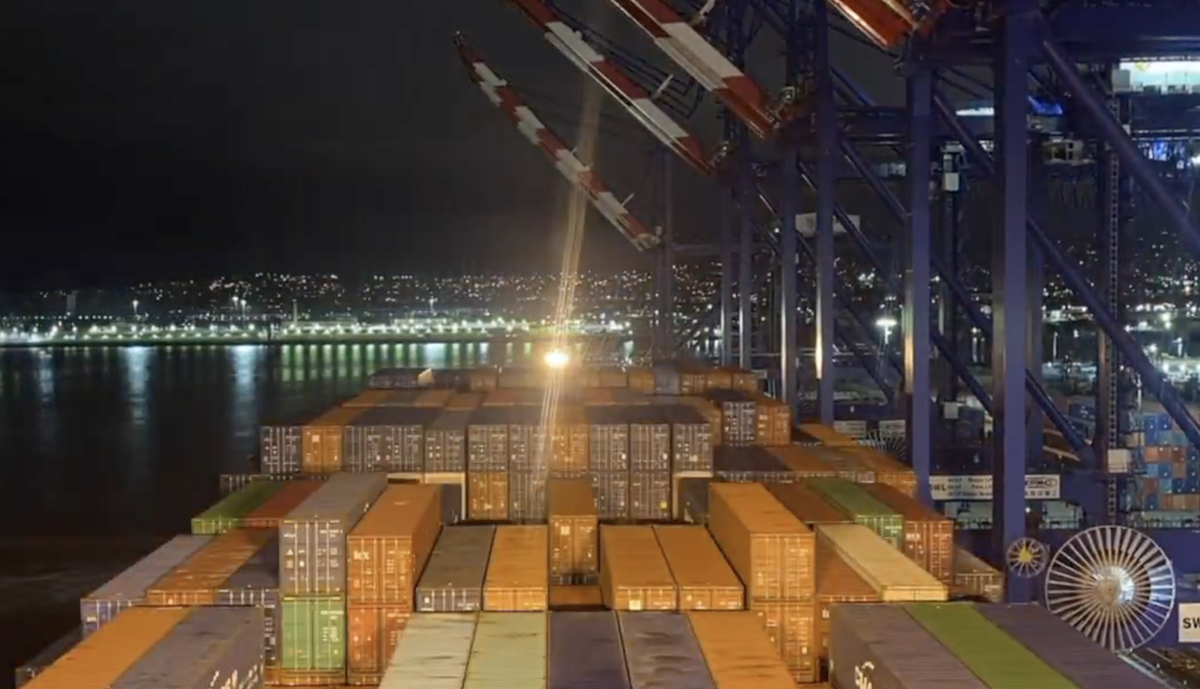
World ocean container spot charges might fall 30% in 2027 as fleet progress outpaces cargo demand and extra ships return to shorter routes by means of the Crimson Sea, based on Xeneta’s newest ocean market outlook.
The freight-rate intelligence supplier additionally forecasts a 5% decline in long-term contract charges, with each projections evaluating full-year 2027 averages towards third-quarter 2026 ranges.
The forecast by Xeneta chief analyst Peter Sand factors to reduction for shippers after three consecutive years during which main disruptions overturned expectations of decrease charges. However the firm cautions that one other shock might once more overwhelm the market’s supply-and-demand fundamentals.
Xeneta expects the worldwide container fleet to develop 6.8% in 2027, with new deliveries including 2.9 million twenty-foot equal items, or TEUs, of capability and scrapping eradicating about 500,000 TEUs. Container demand, in the meantime, is forecast to extend between 2.5% and 4%.
That imbalance might widen as transport traces restore providers by means of the Crimson Sea and Suez Canal. Shorter voyages require fewer vessels than security diversions round Africa, releasing ships for deployment elsewhere. Weekly capability crossing the Crimson Sea reached 467,297 TEUs in October, about half its pre-crisis stage, based on Xeneta. The corporate estimates that the return to shorter routes has already launched 599,000 TEUs of nominal capability throughout 2026, with extra anticipated within the first half of 2027.
Demand can also be prone to lose a few of the momentum generated by precautionary transport this 12 months. World container volumes rose 4.7% within the first eight months of 2026, however Xeneta attributes a lot of that progress to companies shifting items earlier to keep away from gas surcharges and additional disruption.
Asia-U.S. container volumes elevated 11% in August, in contrast with 1.9% progress in inflation-adjusted U.S. retail gross sales. Xeneta expects stock drawdowns to contribute to a gradual begin to 2027, adopted by a weaker peak transport season.
The prospect of decrease charges follows a pointy escalation in transport prices throughout 2026. In keeping with Xeneta, Asia-U.S. West Coast spot charges in October had been 343% above their February 28 stage, instantly earlier than the Center East disaster started, and stood simply 14% beneath their pandemic-era report. Different main outbound trades from the Far East additionally recorded triple-digit spot-rate will increase in the course of the 12 months.
Sand’s evaluation identifies a succession of disruptions: The escalation of the Crimson Sea battle in 2024; U.S. tariffs in 2025, and Center East battle and the closure of the Strait of Hormuz in 2026. Every interrupted expectations that freight charges would soften.
Dangers stay concentrated round gas prices and demanding transport routes. Xeneta says Singapore high-sulphur bunker gas costs have risen 107% since February 27. Common gas surcharges on long-term contracts throughout 4 main Asia trades elevated 42% to $820 per forty-foot equal unit.
Arabian Gulf providers additionally stay closely disrupted. Weekly container capability arriving at Jebel Ali, United Arab Emirates, fell from 423,000 TEUs earlier than the battle to 9,000 TEUs, based on Xeneta. The corporate expects carriers to retain different regional gateways even when the Strait of Hormuz reopens.
The Panama Canal gives extra uncertainty, with the El Niño climatological cycle elevating considerations about water ranges in the course of the dry season in the beginning of 2027. Xeneta says some carriers have already launched Panama surcharges regardless of minimal restrictions.
Service reliability stays a separate problem. World on-time container arrivals fell to 27% within the third quarter of 2026, whereas delayed containers arrived a median of six days late, Xeneta studies. Extreme congestion has been an ongoing concern for Asia and European hubs.
The corporate expects reliability to enhance within the first half of 2027 as capability will increase and demand softens, however sees a ceiling of round 40%. It additionally cautions that higher headline efficiency can replicate cancelled sailings or longer revealed transit instances relatively than a real enchancment in service.
The advantages of falling charges are prone to range considerably by route. Unsurprisingly, Xeneta says cargo progress stays focused on higher-paying outbound, or fronthaul, trades, whereas return-leg volumes lag. China now exports six laden containers for each laden container it imports, in contrast with 3.3 in 2019 — an imbalance that absorbs capability and will assist costs on busy routes whilst the worldwide common declines.
For shippers, the forecast alerts potential value reduction relatively than a uniform discount in freight payments. The result will rely on particular person commerce lanes, publicity to disrupted routes, and the way contracts account for gas surcharges and routing adjustments, Xeneta says.
Why it issues: Ocean transport might turn out to be cheaper with out changing into extra predictable, however battle, gas surcharges and adjustments to main transport routes might nonetheless derail that forecast.
Learn extra articles by Editor right here.
Learn extra:
Strike at Los Angeles-Lengthy Seaside port delayed as union contract talks proceed
North America container imports rise 9% as as freight pricing pressures mount
Maersk raises revenue outlook as earnings surge, however shares slide on expectations miss
Asia-US container charges maintain as carriers search $3,000 November price hikes
ONE lifts revenue forecast to $2 billion as earnings surge
The put up Asia-U.S. West Coast ocean container spot charges up 343% since begin of Iran struggle, says Xeneta appeared first on BigRig.