Knight-Swift Transportation beat third-quarter expectations Wednesday after the market closed.
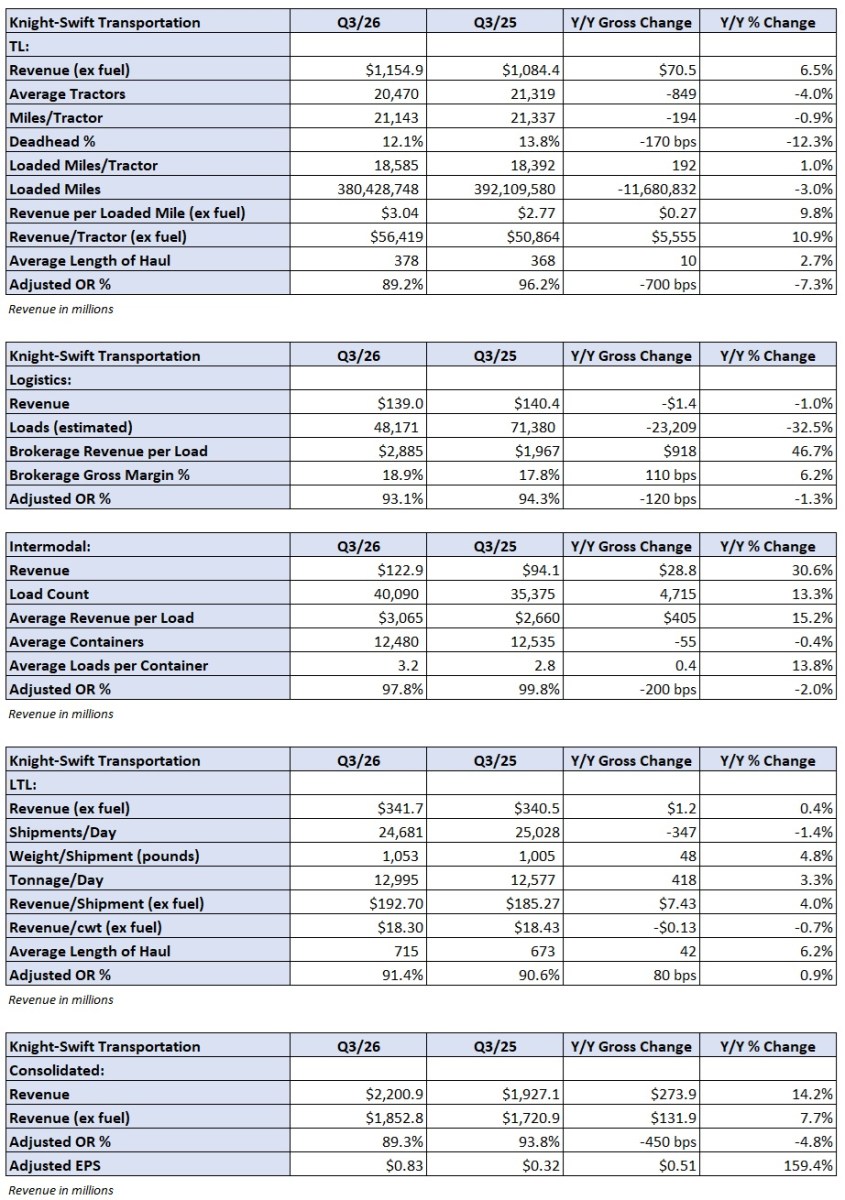
Knight-Swift (NYSE: KNX) reported adjusted earnings per share of 83 cents, 51 cents greater than the year-ago quarter and seven cents higher than the consensus estimate. (Administration’s EPS steerage vary was 71 to 77 cents.)
Income of $2.2 billion was up 14% y/y (up 8% y/y excluding gasoline surcharges) and barely forward of analysts’ expectations for $2.17 billion.
“Much like our outlook final quarter, we anticipate momentum throughout our companies to maintain constructing as charges proceed to be reset, as we keep our value and operational initiatives, and as we anticipate extra seasonal spot and undertaking alternatives than we now have seen in recent times,” mentioned Knight-Swift CEO Adam Miller in a information launch.
The truckload unit noticed a 6.5% y/y income improve (ex-fuel) as an 11% improve in income per tractor was solely partially offset by a 4% decline in common tractors in service. Loaded miles per tractor had been up 1% y/y, an eighth consecutive improve. Deadhead was down 170 foundation factors y/y to 12.1%. Income per loaded mile (ex-fuel) elevated 10% y/y. The metric was up by a mid-teen proportion in its over-the-road service.
The TL unit posted an 89.2% adjusted working ratio, 700 bps higher y/y and in keeping with the midpoint of administration’s steerage vary. U.S. Xpress, which was acquired in 2023, operated at a low-90% adjusted OR within the quarter whereas Knight-Swift’s legacy manufacturers operated at 88%.
Much less-than-truckload income was up lower than 1% y/y (ex-fuel). Tonnage elevated 3% whereas income per hundredweight (ex-fuel) dipped 1%. Will increase in weight per cargo (+5%) and size of haul (+6%) had largely offsetting impacts on yield within the quarter. Income per cargo (ex-fuel) elevated 4%. Contractual renewals had been up by a mid-single-digit proportion.
The LTL unit booked a 91.4% adjusted OR, 80 bps worse y/y.
Knight-Swift issued fourth-quarter adjusted EPS steerage of 78 to 84 cents, which bracketed the 82-cent consensus estimate on the time of the print.
The third-quarter adjusted EPS quantity benefitted y/y from a $22-million discount in web curiosity expense (10 cents per share), a decrease tax price (5 cents per share) and a slight improve in features on tools gross sales (1 cent per share). Nevertheless, the opposite revenue line was down $3.5 million y/y (2 cents per share).
Shares of KNX had been up 4.4% in after-hours buying and selling on Wednesday.
The corporate will host a name at 5:30 p.m. EDT on Wednesday to debate third-quarter outcomes.
Why it issues? Knight-Swift is the nation’s largest asset-based TL service and serves as a bellwether for market tendencies. The corporate’s third-quarter outcomes spotlight that the market has transitioned from a cyclical downturn to a structural restoration.
Extra BigRig articles by Todd Maiden:
- Heartland Categorical sees earnings turnaround in Q3
- Werner Enterprises points Q3 revenue warning
- J.B. Hunt experiences rising pains in Q3
The submit First look: Knight-Swift’s Q3 beats expectations appeared first on BigRig.