J.B. Hunt Transport Companies’ third quarter might show to be a pace bump on the highway to restoration. The corporate beforehand flagged important price pressures, some growth-related, heading into the Thursday print. To satisfy demand, a few of its enterprise models provided sign-on bonuses and improve driver recruitment spending. Some prices seem transitory, whereas others might linger by way of the top of the yr.
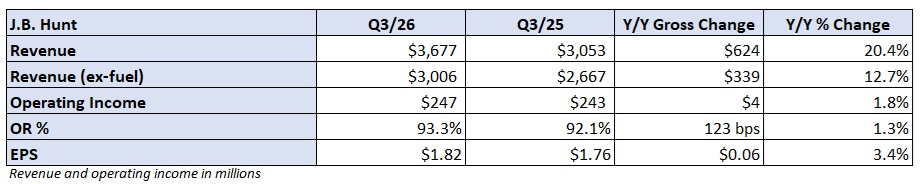
J.B. Hunt (NASDAQ: JBHT) reported third-quarter income of $3.68 billion, which was 20% greater yr over yr and forward of the $3.59 billion consensus estimate. Earnings per share of $1.82 have been 6 cents greater y/y and 1 cent above analysts’ lowered expectations. (The next tax fee was a 4-cent EPS headwind within the interval, partially offset by a 2-cent decline in internet curiosity expense.)
The corporate recognized roughly $45 million in prices at an investor convention in mid-September. A pointy spike in diesel costs, driver hiring prices and elevated cargo claims pressured the corporate to information to a 5% to 10% sequential EPS decline within the third quarter (implying $1.77 on the midpoint of the vary). The precise impression from the gadgets totaled over $50 million within the interval.
Nevertheless, administration instructed analysts on a Thursday night name that “the whole lot [is] enjoying out like a standard cycle,” noting it’s common to incur incremental prices forward of upper pricing and income.
“Any time that we see this strain occurring from a driver setting, [it] usually yields a a lot better pricing setting for the subsequent bid season,” mentioned President and CEO Shelley Simpson.
The brunt of the cost-price mismatch probably occurred in August and September, and will fade because the magnitude of the associated fee strain eases and up to date contractual fee wins bleed by way of to outcomes. It mentioned workplace headcount was down 4.5% y/y within the interval, as driver rely elevated 3.5%.
Gas surcharges function on a one-week lag. Diesel costs have been up sequentially in 9 of the 13 weeks of the third quarter. By month, retail diesel costs dipped 1% sequentially in July, however elevated 10% sequentially in August and one other 15% in September. The near-term headwind will turn out to be an earnings tailwind when costs revert.
The third quarter marked a fifth straight quarter of y/y enchancment in working earnings and EPS. The corporate’s earnings turnaround began within the 2025 third quarter, effectively forward of friends.
Intermodal can exit 2027 working inside margin goal vary
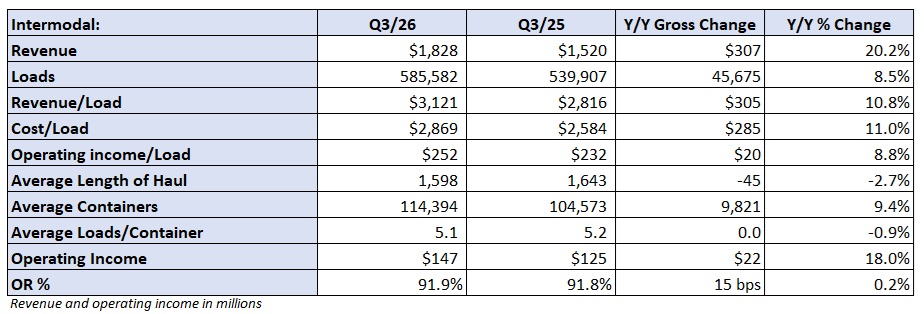
Intermodal income elevated 20% y/y to $1.83 billion as masses have been up 8.5% and income per load elevated 11%.
The interval was up towards a neater quantity comparability to a yr in the past (-1%). By month, shipments grew y/y by 9% in July, 8% in August and 9% in September. Shipments elevated 18% y/y within the East and 1% within the transcontinental community. Whole intermodal carloads have been up 6% y/y on the U.S. Class I railroads within the interval (North American container strikes have been up 5% y/y).
Excluding gas, income per load was up simply 2% y/y. Nevertheless, a 3% decline in size of haul, because of the combine shift to the East, was a modest headwind to yield metric. Administration mentioned it captured low-single-digit contractual fee improve within the 2026 bid season, which ended final month.
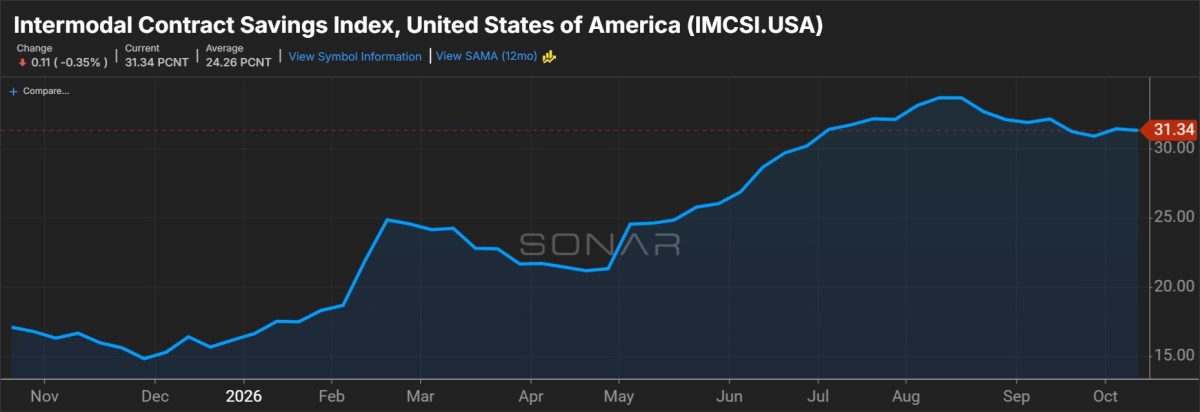
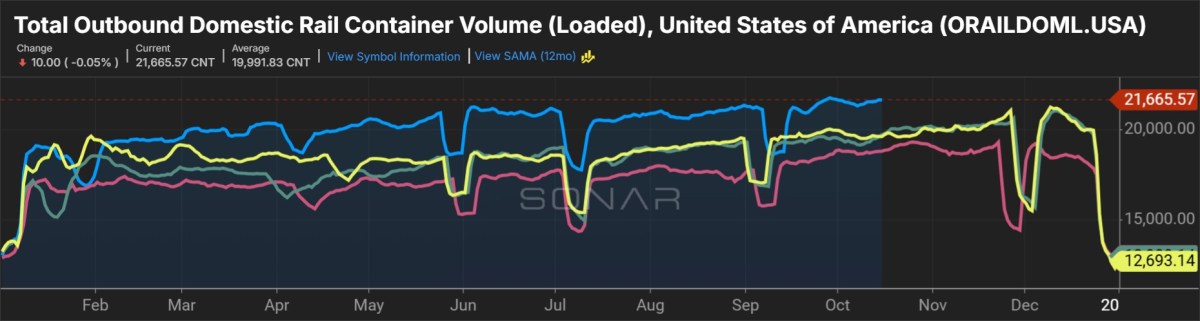
Sonar knowledge exhibits the mode is at present 31% cheaper than truck, which is notably greater than the everyday 10% to fifteen% low cost carried within the East (roughly 25% within the West). Elevated truckload charges and file diesel costs stay ample tailwinds for road-to-rail conversion.
The unit booked a 91.9% working ratio (inverse of working margin), which was 15 foundation factors worse y/y. Greater prices (driver personnel, tools and worker advantages) led to an 11% improve in price per load, offsetting the rise in yield.
The corporate’s container fleet was 92.1% utilized within the quarter, 170 bps higher than within the second quarter and effectively forward of the 83.6% utilization fee within the 2025 third quarter. Nevertheless, common masses per container have been down 1% y/y within the interval, probably as a result of a modest deterioration in rail service.
Improved charges and continued price administration might restore margins to the corporate’s long-term goal vary of 10% to 12% by the top of subsequent yr, administration mentioned.
Devoted a Q3 price sufferer
The devoted unit’s OR deteriorated 360 bps y/y to 91.5%.
Income elevated 11% y/y to $960 million as income per truck per week elevated 10% and common vehicles in service have been up 1%. Income per truck was up simply 3% excluding gas. J.B. Hunt offered service on 425 vehicles within the quarter (970 vehicles year-to-date), however its pipeline stays at an all-time excessive.
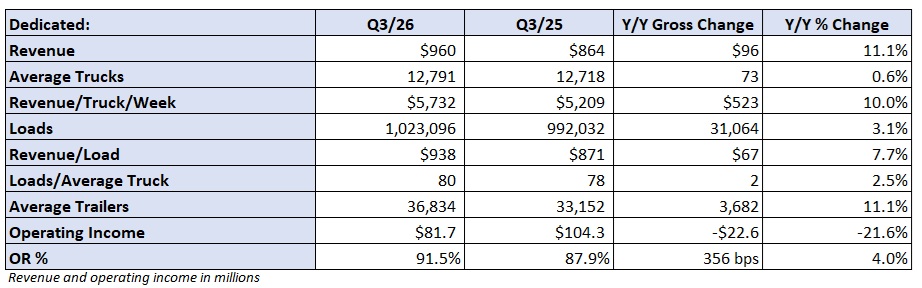
Greater driver prices, group medical claims and insurance coverage premiums have been among the many headwinds within the quarter. It additionally incurred an elevated degree of startup prices at new accounts. Common trailers in service elevated 11% y/y regardless that masses grew simply 3%.
It mentioned it may revisit buyer contracts and recoup incremental prices, like greater driver prices, earlier than the annual rollover.
Brokerage books one other revenue
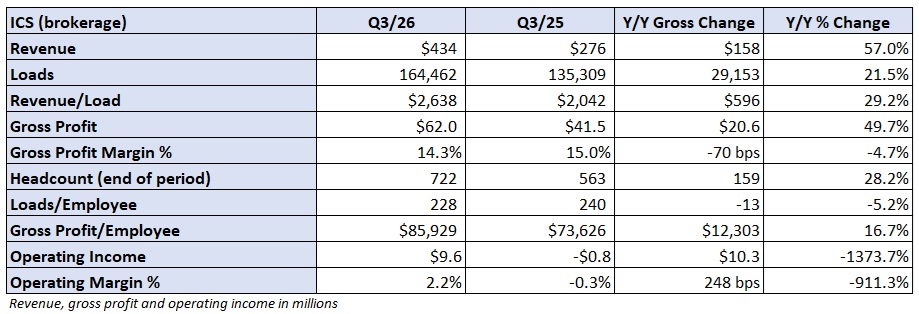
After 13 quarters working within the crimson, the brokerage unit booked a second straight working revenue.
Income elevated 57% y/y as masses grew 22% and income per load jumped 29% (inclusive of gas). A 14.3% gross margin was 70 bps decrease y/y however 180 bps higher than the second quarter. Bought transportation prices (spot charges) cooled following the Fourth of July. Hundreds per worker fell 5% y/y however gross revenue per worker elevated 17%. Headcount was 28% greater y/y.
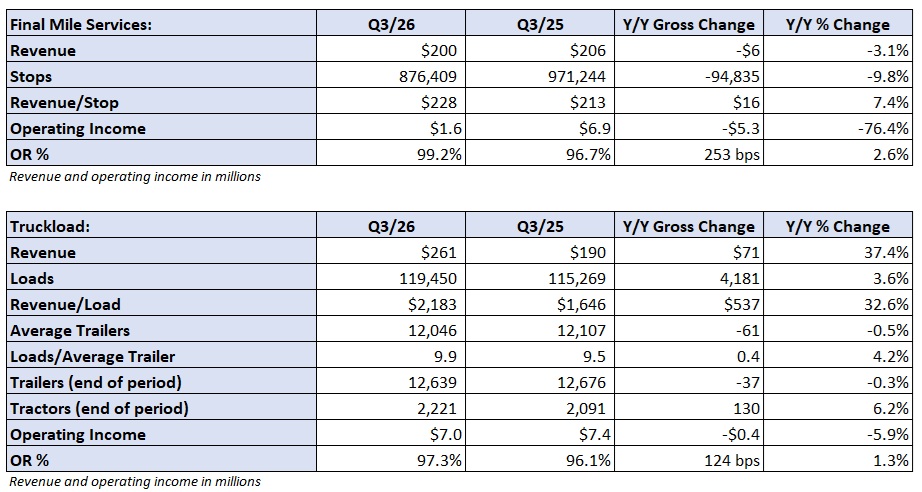
The corporate’s asset-light TL unit returned to profitability after a modest second-quarter loss. The $7-million working revenue was pushed by a 29% y/y improve in income per load (excluding gas) and a 4% improve in trailer utilization (masses per common trailer). The working earnings end result was roughly flat y/y.
Shares of JBHT have been down 3% in pre-market buying and selling on Friday. The inventory fell 14% from its mid-September earnings replace to the Thursday shut.
Why it issues? J.B. Hunt’s quarterly outcomes function a bellwether for the intermodal, trucking and logistics industries. The corporate’s third quarter was a modest slowdown after 4 quarters of sturdy restoration. Nevertheless, a few of the incremental prices that plagued the interval have been probably transitory in nature.
Extra BigRig articles by Todd Maiden:
- LTL charges hit new excessive in Q3, shifting greater in This autumn
- Cass: TL linehaul charges up 10% in September, cargo counts stay constructive
- Yellow Corp., Teamsters choose WARN Act claims
The submit J.B. Hunt experiences rising pains in Q3 appeared first on BigRig.