
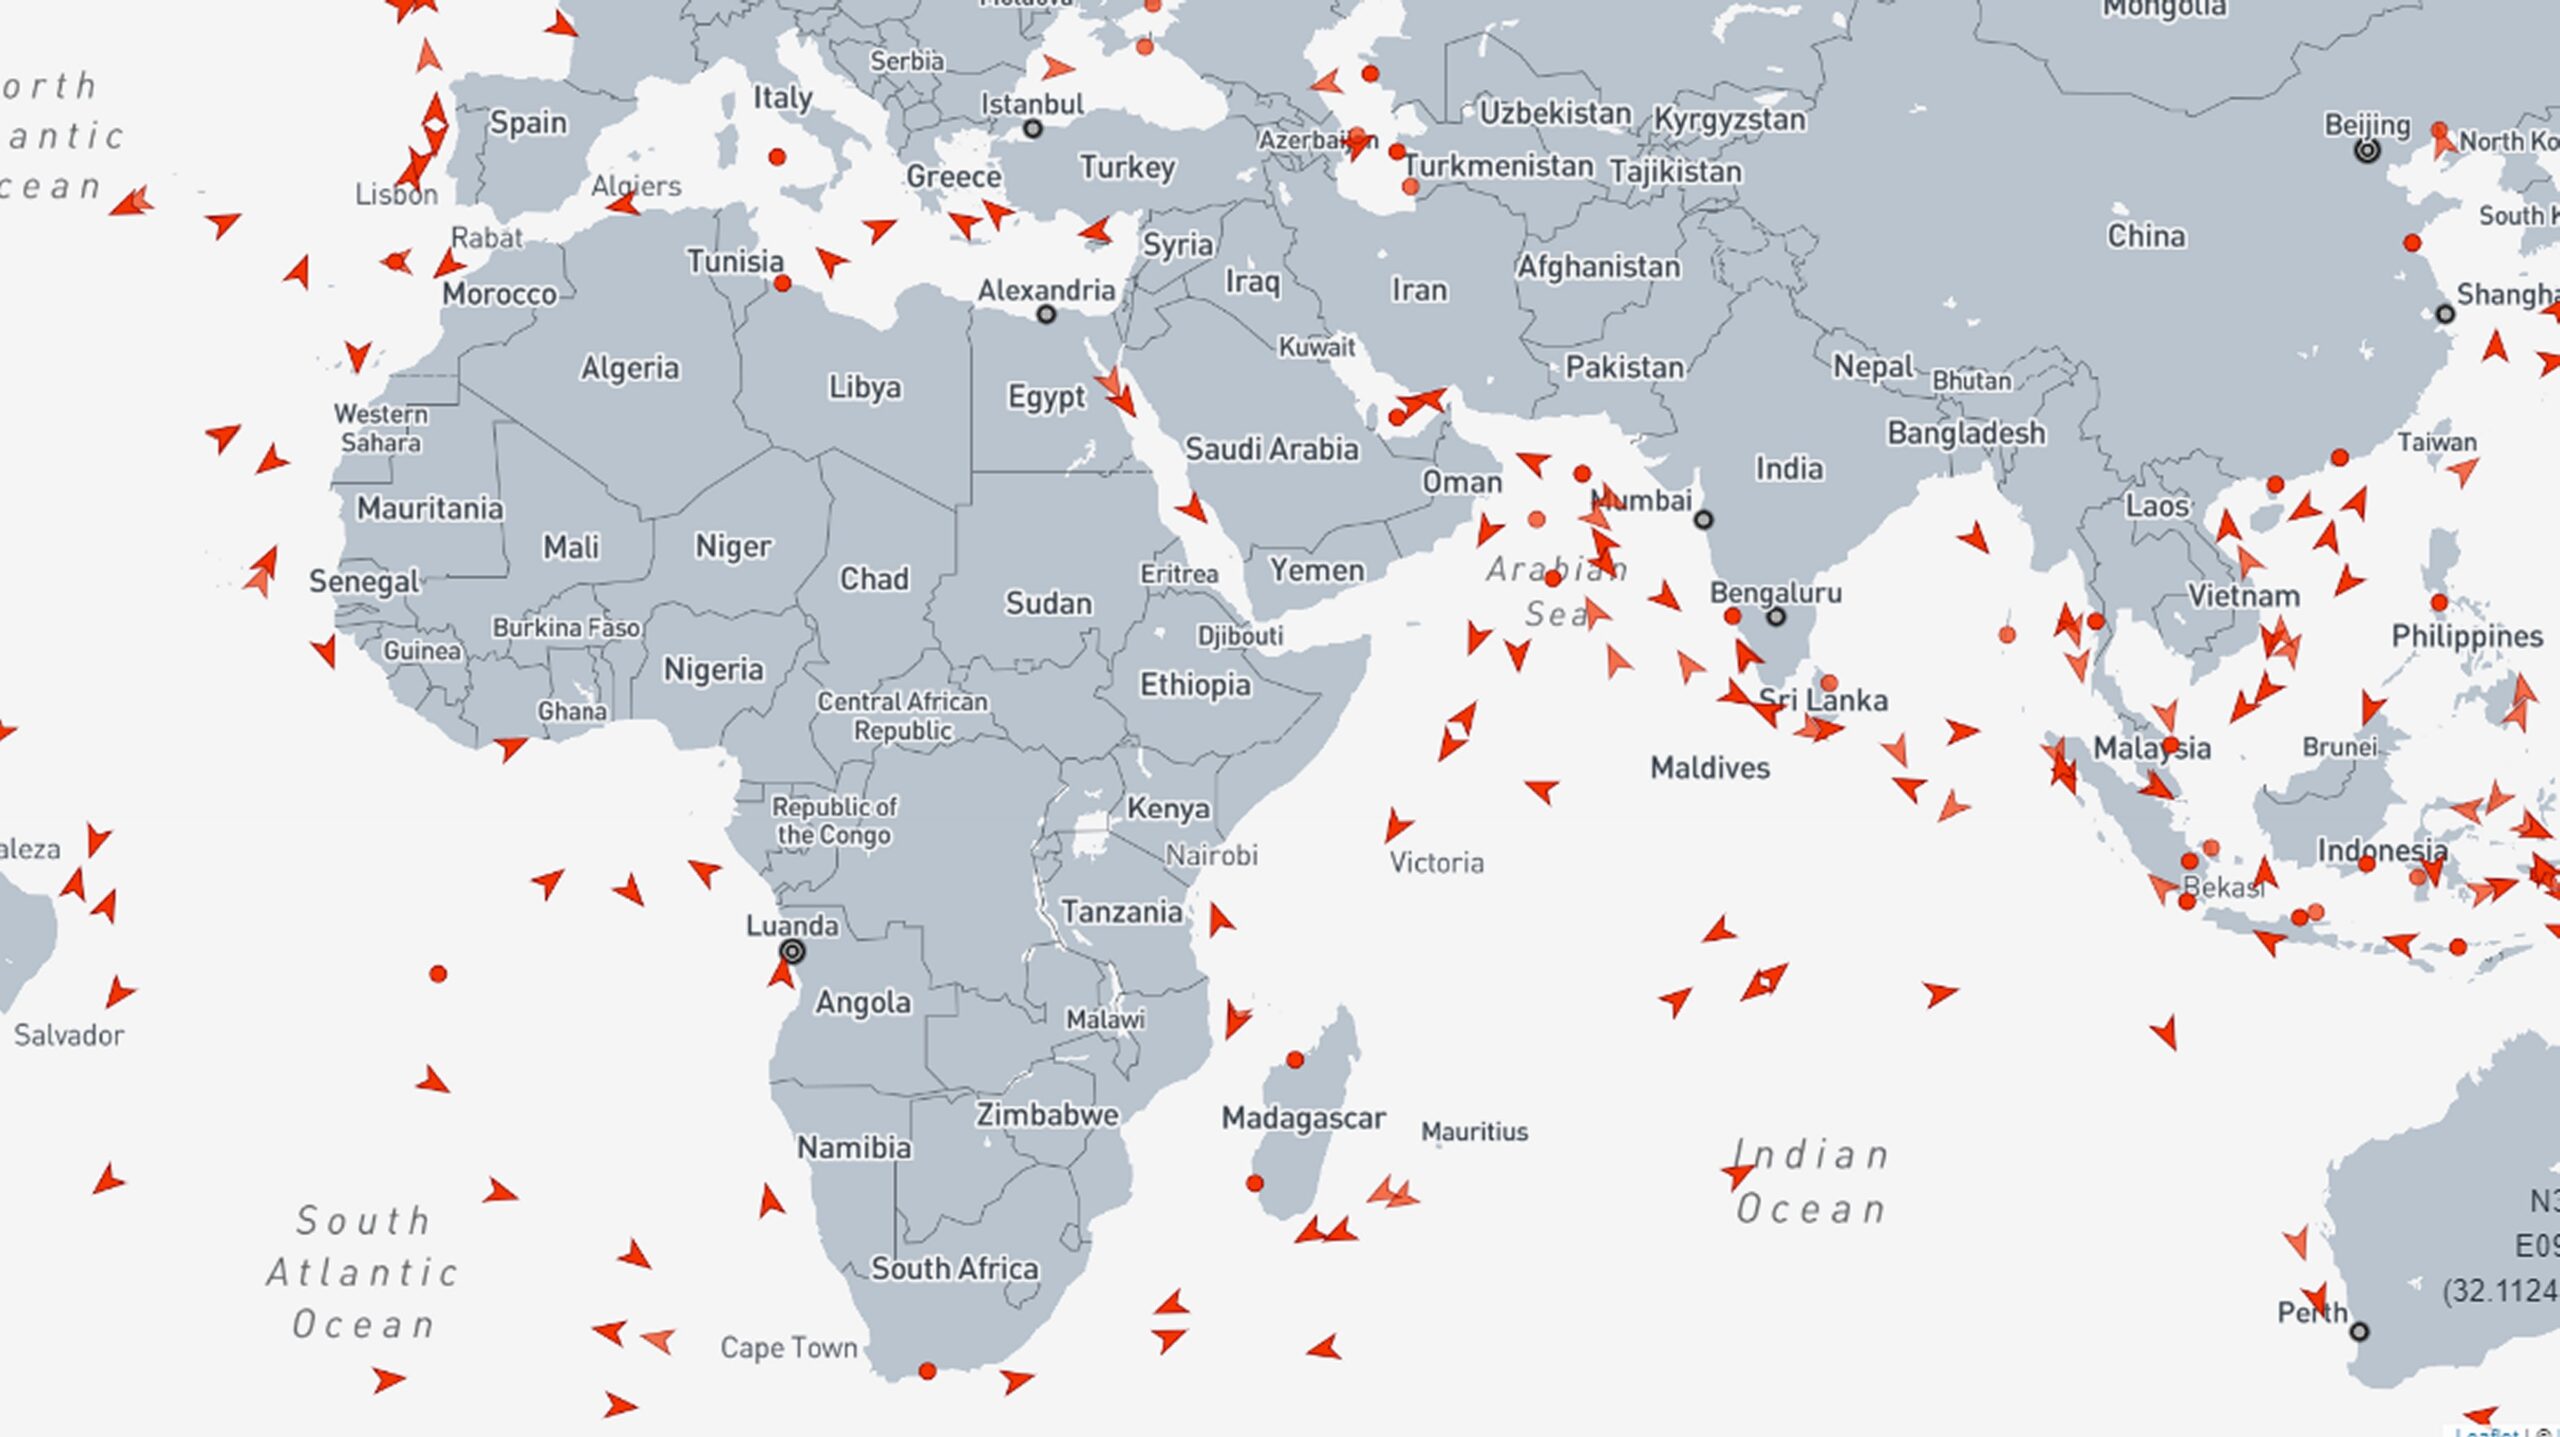
Endlessly for the Purple Sea disaster, detours round Africa’s Cape of Good Hope are absorbing much more vessel capability and pushing up spot charges throughout a number of delivery segments.
Freight fallout started with container ships. It’s now considerably impacting product tankers — the vessels that transport gasoline, diesel, jet gasoline, naphtha and different petroleum merchandise.
Bigger product tankers that do long-haul runs are diverting round Africa in growing numbers. These ship varieties embody LR1s (with capability of 55,000-79,999 deadweight tons or DWT) and LR2s (80,000-119,000 DWT).
Prolonged transit occasions for long-haul product tankers are having the knock-on impact of mountain climbing demand for regional alternative shipments utilizing short-haul vessels often called MRs (25,000-54,999 DWT).
Gas costs are being effected, as effectively. “The present halt of east-to-west diesel movement by the Purple Sea and Suez Canal has already pushed diesel costs in Europe larger, with additional will increase anticipated as deliveries gradual as a result of vessels rerouting round Africa,” mentioned Frode Mørkedal, delivery analyst at Clarksons Securities, in a consumer notice.
Tanker charges ‘definitively seeing upward strain’
Evercore analyst Jon Chappell mentioned in a report on Wednesday, “Longer voyages as extra tankers bypass the essential Purple Sea/Suez Canal chokepoint will additional add to ton-miles [volume multiplied by distance], probably inflicting huge disruption to commerce routes and including extra potential upside to identify charges which can be already supported by sturdy fleet utilization.”
In response to Deutsche Financial institution analysts Amit Mehrotra and Chris Robertson, “Container freight charges have been one of many first to maneuver on the Purple Sea disruption, however we are actually definitively seeing upward strain on each mid-sized crude tanker and long-range and medium-range product tanker charges.”
In response to Eirik Haavaldsen of Pareto Securities, “Because it stands at the moment, no product tankers look set to make use of the Suez Canal throughout the first half of February — and it will suggest near-zero middle-distillate arrivals from the Center East Gulf and India to Europe throughout that point.
“Because the EU ban on Russian cargoes in Q1 2023, these imports have been within the 800,000 to 1.1 million barrel-per-day [b/d] vary, and we’re consequently going to both see important inventory attracts or the necessity for alternative cargoes.
“To date, we have now seen a rise in [EU] diesel imports from the U.S., which have reached 350,000-400,000 b/d up to now in January versus 100,000-200,000 b/d final 12 months,” mentioned Haavaldsen.
Product tanker charges close to cyclical highs
Spot charges for modern-built (2015 or later) LR2s averaged $84,800 per day on Wednesday, up 132% 12 months on 12 months (y/y), in response to information from Clarksons.
LR2 price good points are being led by the Center East Gulf-Europe route — the commerce straight affected by Houthi assaults within the Purple Sea — with modern-built LR2 spot charges on this route now averaging $92,100 per day.
“Product tanker charges have continued to hole up,” mentioned Jefferies analyst Omar Nokta on Wednesday. “LR2s particularly have damaged out. With the vessels fastened to the European market most certainly to divert across the Cape of Good Hope, many of those will likely be laden for longer and result in a good tighter stability within the coming weeks.
“Present LR2 earnings are approaching highs seen throughout this cycle,” mentioned Nokta, noting that they’re slightly below common highs of $90,000 per day briefly reached in December 2022.
Charges for modern-built LR1s averaged $61,600 per day on Wednesday, in response to Clarksons, double charges a 12 months in the past. The Purple Sea state of affairs is “offering a catalyst for the spike in [LR1] charges,” mentioned ship brokerage BRS on Monday.
Charges for modern-built MRs have been at $45,600 per day, up 84% y/y, in response to Clarksons.
BRS famous that the Purple Sea restrictions for LR tankers “elevate MR utilization … as Asia and Europe flip to short-haul trades to cowl up for his or her shortfall in longer-haul arbitrage inflows.”
Product tanker shares don’t mirror charges but
The Purple Sea disaster has pushed up shares of U.S.-listed product tanker homeowners, but these equities haven’t risen to the identical extent as freight charges.
Shares of Ardmore Delivery (NYSE: ASC) rose 5% on Wednesday and have been up 15% 12 months to this point (YTD). Scorpio Tankers (NYSE: STNG) was up 4% Wednesday, 14% YTD. Torm (NASDAQ: TRMD) rose 1% Wednesday, 18% YTD.
“Within the fairness market, valuation doesn’t mirror latest price enhancements or the prospect of a stronger market in 2024,” wrote Mørkedal on Monday. “We imagine that product tanker equities provide wonderful danger/reward as a result of little of the continuing power has been priced in.”
Click on for extra articles by Greg Miller
Associated articles:
- Container spot charges rocket even larger as Purple Sea disaster drags on
- Purple Sea battle worsens, forcing extra ship detours round Africa
- As Purple Sea danger spooks container delivery, tankers stay unfazed
- West Coast delivery charges surge as Purple Sea fallout goes world
- Container delivery charges spike as Purple Sea disaster attracts first blood
- How protected is Purple Sea? Totally different delivery strains have completely different solutions
- US-led forces in Purple Sea will likely be defensive ‘freeway patrol’
- Purple Sea fallout a lot higher for containers than tankers, bulkers
- Purple Sea chaos ought to enhance tanker and container delivery charges
- Why assaults on container ships precipitated container shares to leap
The publish Delivery fallout from Purple Sea disaster spreads to product tankers appeared first on BigRig.