

Regulatory authorities continued to power out non-compliant capability within the second quarter, making a “speedy development in truckload market situations,” based on Knight-Swift Transportation. The provider reported better-than-expected outcomes on Wednesday, highlighted by contract charges that climbed all through the interval and a young rejection fee that was twice the business common. It expects the optimistic momentum to accentuate beginning in September and to hold by means of the remainder of the 12 months.
“We’ve simply by no means seen the FMCSA, the DOT with the push that they’re making on cleansing up our business and taking the non-compliant, the dangerous actors out of it,” mentioned CEO Adam Miller on a Wednesday night name with analysts.
He believes the change the business is experiencing is “sturdy” and “raises the ground” for charges within the subsequent downturn.
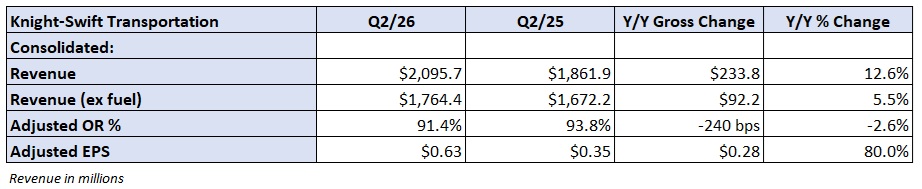
Knight-Swift (NYSE: KNX) reported second-quarter adjusted earnings per share of 63 cents, 28 cents greater 12 months over 12 months and 12 cents higher than the consensus estimate. (Administration’s EPS steering vary was 45 to 49 cents.)
Income of $2.1 billion was 13% greater y/y and forward of the $2.04 billion consensus estimate. Income was up 6% y/y excluding gasoline surcharges.
Inflationary TL fee cycle simply starting
Truckload income elevated 3% y/y to $1.1 billion as a 6% improve in income per tractor was solely partially offset by a 3% decline in common vans in service.
The provider has improved asset utilization by means of enhanced load planning instruments. Deadhead was down 140 bps y/y and 70 bps sequentially. Loaded miles per tractor (up 0.2% y/y) improved y/y for a seventh straight quarter. Earlier than including any new tractors, administration famous that there’s vital alternative to boost utilization, notably since some vans stay unseated.
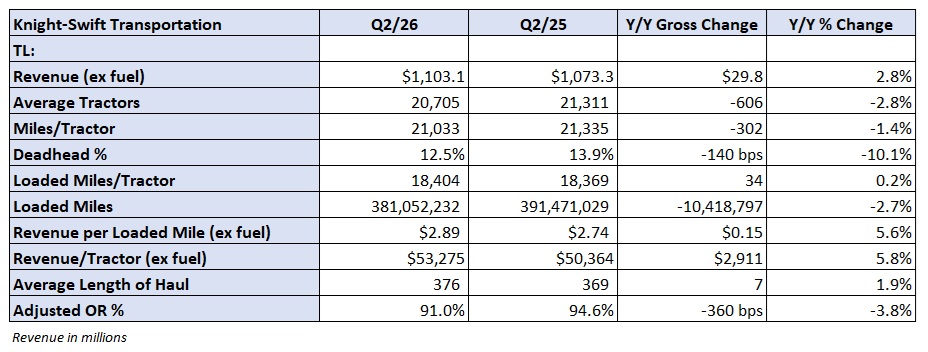
Income per loaded mile elevated 5.6% y/y (excluding gasoline) to $2.89. The metric is “simply starting to get well” as contract charges roll over. Many of the fee implementations within the quarter got here from bids negotiated earlier this 12 months and didn’t mirror a tighter provide backdrop.
Fee per loaded mile accelerated from low-single digits in April to eight% in June. (The over-the-road fleet noticed double-digit will increase in June.) The June quantity had the advantage of some challenge freight, but it surely additionally included a headwind from devoted (28% of the TL fleet) the place fee adjustments are much less risky and listed to inflation.
The speed image continues to enhance. The provider is getting double-digit fee will increase on latest bids, and its spot market publicity is as much as 15% from 10% in the beginning of the 12 months.
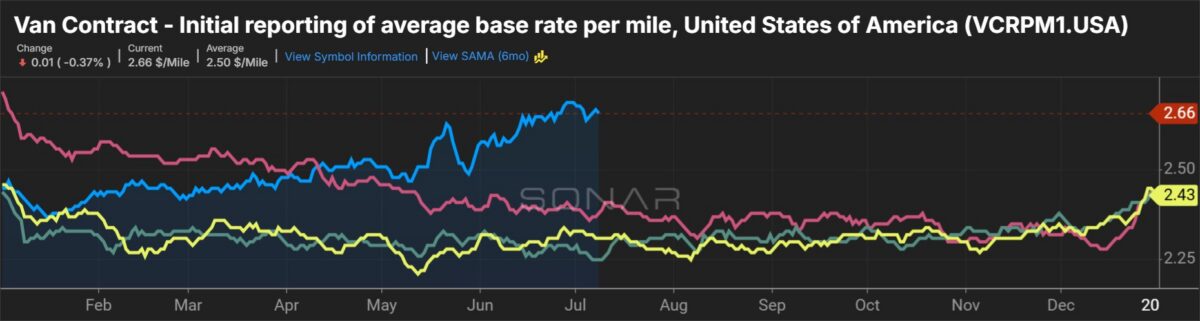
The TL unit posted a 91% adjusted working ratio (a 9% adjusted working margin), which was 360 foundation factors higher y/y. US Xpress’ over-the-road fleet was worthwhile for the primary time for the reason that 2023 acquisition.
Knight-Swift’s TL steering requires a mid-single-digit y/y income improve within the third quarter, with the adjusted OR bettering 650 to 750 bps y/y (implying an 89.2% adjusted OR). Truck depend is predicted to be steady sequentially (decrease y/y), with utilization additionally remaining degree. Greater charges are the catalyst for the y/y income improve.
Driver pay to creep, not rip greater near-term
Administration flagged driver pay as a creeping headwind however famous a number of methods to reinforce whole driver compensation. It mentioned it didn’t claw again any of the prior wage will increase from the final upturn at the same time as charges fell 20%-plus by means of the downturn. The corporate nonetheless has an extended technique to go to revive margins. It reported sub-80% ORs over the last peak.
Knight-Swift is barely planning true wage hikes in choose markets as there isn’t a present must implement broad-based will increase. Improved asset utilization (extra paid miles for drivers) will increase current driver pay packages. It famous that the labor market is looser than it was in the course of the prior upturn and that it’s not competing towards authorities stimulus prefer it did in 2021.
Different Q2 section outcomes, Q3 outlook
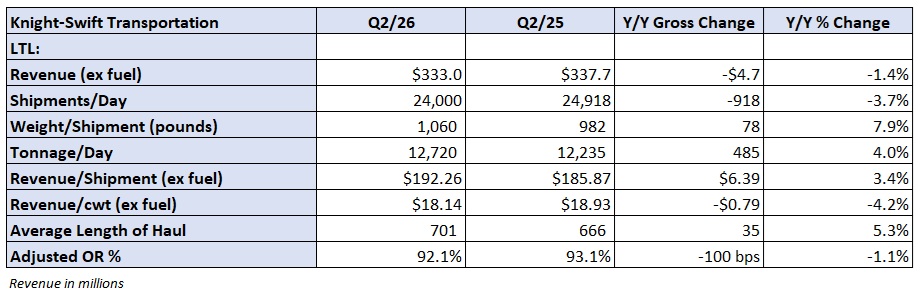
Much less-than-truckload income declined 1% y/y to $333 million as a 4% tonnage improve was offset by a 4% decline in yield (ex-fuel). Shipments per day had been down 4% y/y, however the declines lessened because the quarter progressed (down 6.5% y/y in April, down 3.2% in Could and down 1.3% in June). Non permanent embargoes to attain desired service ranges and a altering freight combine drove the declines.
Weight per cargo was up 8% y/y, which dragged down the yield metric. Nonetheless, the yield headwind was partially offset by a 5% improve in size of haul. The corporate mentioned contractual fee will increase had been up once more by a mid-single-digit proportion within the quarter.
The unit recorded a 92.1% adjusted OR, 100 bps higher y/y.
Income is predicted to extend y/y by a low-single-digit proportion within the third quarter, with an adjusted OR within the low-90% vary.
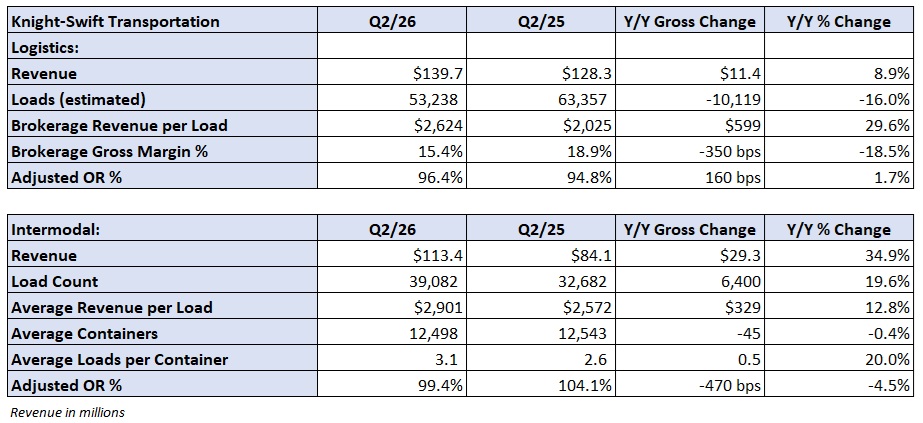
Logistics income elevated 9% y/y as a 30% improve in brokerage income per load was partially offset by a 16% decline in volumes. The corporate mentioned the amount weak point was pushed by “additional enhancements to our rigorous provider screening practices.” Elevated bought transportation prices (gross margin eroded 350 bps y/y) resulted in a 96.4% adjusted OR, 160 bps worse y/y. The unit is predicted to see regular income and margin developments (sequentially) within the third quarter.
Intermodal returned to profitability at a 99.4% adjusted OR. Income was up 35% y/y as volumes grew 20% and income per load elevated 13%. Within the third quarter, intermodal income is predicted to extend by a low-single-digit proportion sequentially (roughly 25% greater y/y), with the OR coming in barely higher than the second quarter.
Knight-Swift issued third-quarter adjusted EPS steering of 71 to 77 cents, which was higher than the 71-cent consensus estimate on the time of the print.
The second-quarter adjusted EPS consequence excluded a number of acquisition-related, restructuring, severance and non-cash impairment prices. The interval benefitted from decrease curiosity expense and better good points on tools gross sales (a 5-cent y/y tailwind).
Shares of KNX had been off 0.5% in after-hours buying and selling on Wednesday.
Why it issues? Serving as a bellwether for TL market developments, Knight-Swift is the nation’s largest asset-based provider. The corporate’s second-quarter outcomes spotlight that the market has transitioned from a cyclical downturn to a structural restoration.
Extra BigRig articles by Todd Maiden:
- Ahead Air secures deal to maintain not less than 50% of $250M account
- Cass: TL linehaul charges advance in June, quantity inflection delayed
- ArcBest broadcasts layoffs, closing 10 LTL terminals
The put up Regulatory cleanup fuels Knight-Swift’s bullish outlook appeared first on BigRig.