
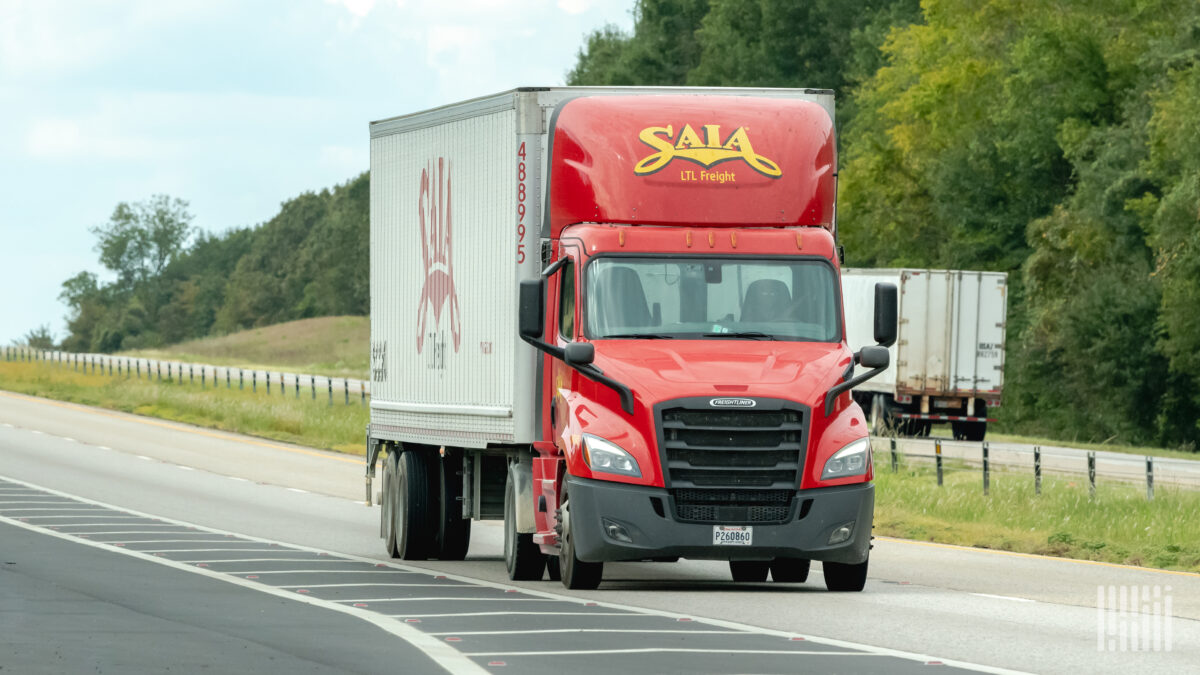
Much less-than-truckload provider Saia’s shares have been off 12% in noon buying and selling on Thursday following a better-than-expected second-quarter report that was muted by administration’s softer third-quarter margin outlook. The corporate has made actual property investments totaling over $1 billion lately, and its new areas are nonetheless working to shut the profitability hole to the remainder of the community.
Saia (NASDAQ: SAIA) reeled in its full-year margin outlook on a Thursday name with analysts. It now expects to hit the decrease finish of a steerage vary calling for 100 to 200 foundation factors of year-over-year enchancment.
“Our sturdy second quarter outcomes spotlight the continued enhancement of our expanded service providing, disciplined execution and the dedication of our crew members,” mentioned Saia CEO Fritz Holzgrefe. “We achieved report income and tonnage, together with a second-quarter report in shipments, reflecting stable progress throughout our community.”
The Johns Creek, Georgia-based firm reported second-quarter earnings per share of $3.51 on Thursday earlier than the market opened. The end result was 84 cents larger y/y and 12 cents higher than the consensus estimate. A decrease tax fee in comparison with the prior-year quarter was a 2-cent tailwind. A $3 million decline in internet curiosity expense was an 8-cent tailwind.
Income was 17% larger y/y at 957 million, largely in step with consensus. Each tonnage and yield elevated by 8% y/y. (Yield was down 2% excluding gas surcharges.)
The tonnage enhance was pushed by a 4% enhance in each cargo counts and cargo weights. Tonnage was up 6.9% y/y in April, up 8.4% in Could and 9.9% larger in June. July tonnage was 7.5% larger y/y.
Saia carried out a 7.1% basic fee enhance on July 6. The rise was 120 bps larger and three months sooner than final yr’s fee bump. Administration mentioned that GRI implementations create some near-term volatility in cargo counts as shippers assess their choices. Taking a look at tonnage on a two-year-stacked comparability to mute the impression of prior-year outcomes, Saia’s tonnage has remained in a variety of plus-8% to plus-9% over the previous three months.
(Saia’s prior-year comps vary from largely adverse to barely constructive for the remainder of the yr.)
Administration additionally defined the two% y/y yield decline, which was a little bit of an outlier in comparison with friends. Increased cargo weights and a decrease size of haul (down 1% y/y) have been headwinds to income per hundredweight. It mentioned excluding these impacts, and the Los Angeles market the place cargo counts have been gentle (nonetheless down 2.5%), internet yield was possible up 3% y/y.
Contractual renewals averaged 10.7% within the second quarter (up 15.8% on a two-year-stacked comp). The end result was effectively forward of friends, however administration concedes its providing is priced beneath the market relative to the service ranges it gives.
Saia reported an 86.9% working ratio (inverse of working margin) within the quarter, 90 bps higher y/y. This was the primary y/y OR enchancment because the 2024 first quarter and forward of administration’s implied steerage for an 87.5% OR.
The provider often sees margins decelerate by 150 to 200 bps from the second to 3rd quarter, but it surely expects simply 100 bps of sequential degradation this yr. The information implies an 87.9% OR within the third quarter, which might be 30 bps worse y/y (excluding the OR impression from a achieve on the sale of actual property within the 2025 third quarter). Administration pointed to a pull ahead within the timing of wage will increase as the explanation for the perceived weaker-than-expected information.
Additionally, the addition of recent service facilities has been a drag on margins. Since 2022, Saia has added 33 new areas and expanded or relocated one other 25 terminals. The actions have made it a real nationwide provider, rising its door rely by 25%. Margins at these areas improved roughly 300 bps in the course of the second quarter, however at a low-90% OR, the amenities nonetheless path the corporate’s legacy community.
A full-year internet capex vary of $350 million to $400 million was reiterated. Internet capex was $544 million in 2025 and $1.05 billion in 2024.
Shares of SAIA have been down 11.7% at 12:15 p.m. EDT on Thursday in comparison with the S&P 500, which was up 1.3%.
Why it issues? Saia is one of some publicly traded LTL carriers. Its quarterly outcomes present perception right into a subsegment of trucking the place few public datasets exist.
Extra BigRig articles by Todd Maiden:
- XPO’s Q2 earnings beat expectations behind sturdy LTL efficiency
- ArcBest’s Q2 a step on path to restoration
- Regulatory cleanup fuels Knight-Swift’s bullish outlook
The submit Saia’s Q3 margin steerage disappoints buyers appeared first on BigRig.