XPO as soon as once more outperformed expectations, pushed by increased volumes and stronger pricing that proceed to amplify the impression of its operational effectivity initiatives.
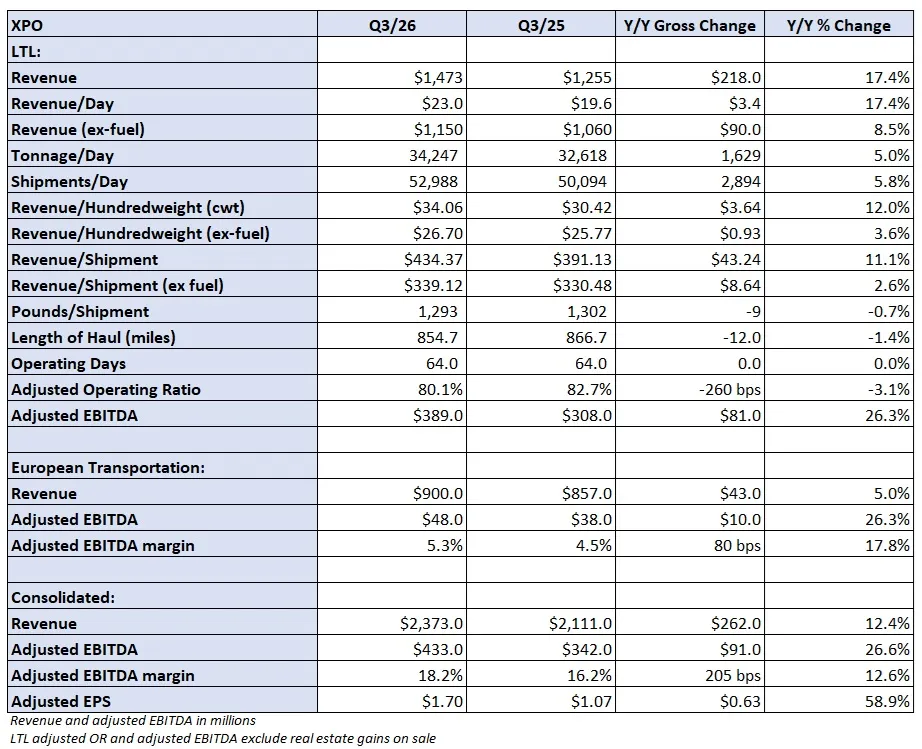
XPO (NYSE: XPO) reported third-quarter adjusted earnings per share of $1.70, which was 13 cents forward of the consensus estimate and 63 cents increased 12 months over 12 months. The adjusted EPS quantity excluded transaction and restructuring prices, amongst different gadgets.
Consolidated income of $2.37 billion was 12% increased y/y however $10 million beneath analysts’ expectations.
Much less-than-truckload income elevated 17% y/y to $1.47 billion. Income was 9% increased excluding gas surcharges. (Diesel gas costs had been 48% increased y/y within the quarter.)
The income improve in LTL was pushed by a 5% y/y improve in tonnage and a 12% improve in yield (income per hundredweight). The tonnage consequence stemmed from a 6% improve in every day shipments and a 1% decline in weight per cargo. Yield (ex-fuel) elevated 4% y/y, with income per cargo (ex-fuel) up 3% y/y.
The corporate’s freight combine consists of extra shipments from native accounts (SMBs), that are sometimes lighter however produce higher margins. September marked the ninth straight month of growth for the U.S. manufacturing complicated, which is a major supply of LTL freight. Administration mentioned a current survey of its prospects confirmed half of the respondents anticipate stronger demand within the first half of 2027 versus the second half of 2026.
Tonnage tendencies within the quarter outperformed regular seasonality.
On a y/y comparability, tonnage was up 5.8% in July, 3.7% in August and 5.4% in September. October tonnage is working 6.5% increased y/y. Tonnage progress is accelerating on a two-year-stacked comparability after turning constructive in September (+0.7%) to up 2.7% to this point in October. The prior-year comparisons are barely simpler in November and December.
The unit booked an 80.1% adjusted working ratio, which was 260 foundation factors higher y/y and consistent with administration’s steerage (sub-81%). The OR consequence was simply 20 bps worse than the second quarter, handily outpacing the historic development. The corporate usually sees 200 to 250 bps of OR degradation from the second to the third quarter. Quite a lot of pricing and working effectivity initiatives are driving the development.
XPO’s European transportation section reported a 5% y/y improve in income to $900 million. Adjusted EBITDA of $48 million was 26% increased y/y.
The corporate will host a name at 8:30 a.m. EDT on Thursday to debate third-quarter outcomes.
Why it issues? XPO is one of some publicly traded LTL carriers. Its quarterly outcomes present perception right into a subsegment of trucking the place few public datasets exist.
Extra BigRig articles by Todd Maiden:
- Previous Dominion’s tonnage turns constructive; restoration wants demand inflection
- Insurance coverage claims changes tank Landstar’s in any other case sturdy Q3
- Werner Enterprises sees price headwinds lingering into Q1
The publish XPO’s pricing, working initiatives drive Q3 beat appeared first on BigRig.