
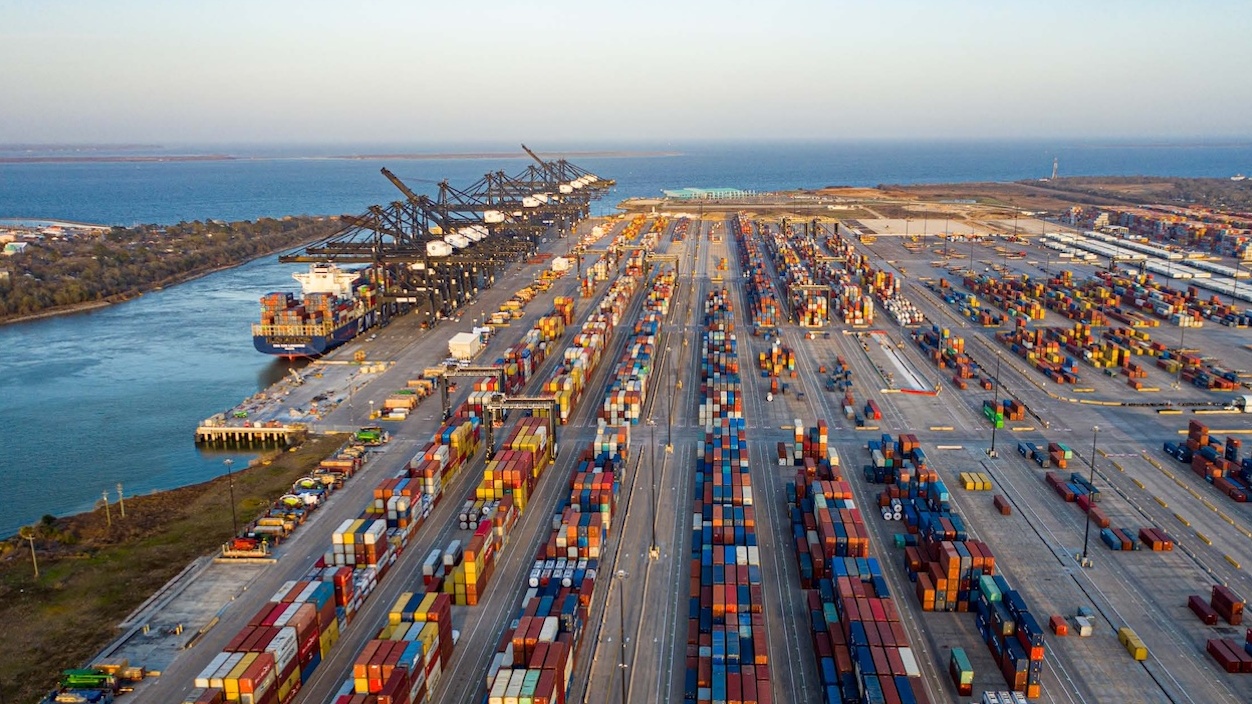
U.S. containerized imports rose 3.8% from July to 2.60 million TEUs in August, supported by increased volumes at main East, Gulf and West Coast ports and broad features throughout sourcing international locations.
Imports climbed 3.8% from July to 2.60 million TEUs as features at East, Gulf and West Coast gateways coincided with a broad improve in sourcing-market volumes and rising port transit delays.
Import quantity reached 2,603,709 twenty-foot equal models (TEUs) in August, the third-highest month-to-month quantity on document, as shippers moved extra cargo by means of main gateways regardless of rising uncertainty over tariffs, Center East transport disruptions and new Panama Canal capability constraints.
Imports rose 3.8% from July and three.3% from August 2025, in line with Descartes Datamyne knowledge. Solely Could 2022, when imports totaled 2,622,465 TEUs, and July 2025, with 2,621,910 TEUs, produced bigger month-to-month volumes.
The August complete was additionally 21.5% above the pre-pandemic stage recorded in August 2019. Whereas cumulative imports by means of the primary eight months of 2026 remained down 0.4% from the identical interval a 12 months earlier, the August acquire narrowed the year-to-date deficit and pointed to resilient late-summer import demand.
The month-over-month improve was notable as a result of it reversed July-to-August declines recorded in each 2024 and 2025. It additionally got here as importers face a extra difficult working setting, together with expanded U.S. tariff publicity, disruption across the Strait of Hormuz, elevated Crimson Sea safety danger and decreased Panama Canal transit availability.
Port volumes broaden
The nation’s 10 largest container gateways dealt with 84.6% of U.S. containerized imports in August and collectively elevated quantity by 80,661 TEUs, or 3.8%, from July. Eight of the ten ports posted month-to-month features.
New York/Newark recorded the biggest improve, up 24,122 TEUs, or 7.2%, from July. Savannah adopted with a acquire of twenty-two,761 TEUs, or 9.2%, whereas Lengthy Seaside elevated by 12,945 TEUs, or 2.8%.
Within the Gulf area, Houston posted an 8,569-TEU improve, up 4.7%. New York-New Jersey gained 8,548 TEUs, or 18.1%. Charleston rose 5,751 TEUs, Tacoma elevated 4,829 TEUs and Norfolk added 511 TEUs.
Solely Oakland and Los Angeles reported quantity declines among the many prime 10 gateways. Oakland fell 5,628 TEUs, or 7.4%, and Los Angeles slipped 1,748 TEUs, or 0.4%.
The distribution of the features helped East and Gulf Coast ports regain some share of complete U.S. import quantity. They accounted for 40.7% of imports in August, up from 39.8% in July. West Coast ports accounted for 43.9%, down from 45% a month earlier.
The shift was modest however mirrored the outsized August features at New York/Newark and Savannah, two of the nation’s largest East Coast gateways.
Delays rise at each main gateway
Stronger throughput was accompanied by increased transit delays throughout all 10 main ports, in line with the report.
Houston and Seattle registered the largest will increase. Houston’s common delay rose 1.5 days, from 4.3 days to five.8 days, whereas Seattle elevated by the identical quantity, from 6.1 days to 7.6 days. Savannah’s delay rose 1.3 days to six.1 days.
Los Angeles, Norfolk, New York-New Jersey, Tacoma, Oakland, Charleston and Lengthy Seaside additionally posted extra average delay will increase.
Descartes defines port transit delay because the distinction between the estimated arrival date initially listed on a invoice of lading and the date on which it receives U.S. Customs and Border Safety-processed bill-of-lading knowledge.
The broad-based rise in delays means that operational stress intensified as imports climbed throughout the late-summer transport season.
Gulf Coast momentum continues
Gulf Coast ports continued to achieve quantity in August, dealing with 252,675 TEUs, a 4.2% improve from July.
The August complete was 11.7% above the Gulf Coast’s rolling 12-month common of 226,120 TEUs and was just one.9% beneath the area’s 2026 excessive of 257,564 TEUs set in Could. August represented the second-highest complete within the interval coated by the report and prolonged a rebound that started in July.
The rise is important as a result of the area has change into a bigger a part of importers’ routing and contingency planning as East and Gulf Coast gateways gained share.
China imports rise, however share slips
U.S. imports from China totaled 884,318 TEUs in August, up 1.3% from July and 1.7% from August 2025. Nonetheless, China-origin imports remained 13.5% beneath the document 1,022,913 TEUs dealt with in July 2024. China accounted for 34% of all U.S. containerized imports in August, down from 34.8% in July, indicating that imports from different sourcing places expanded extra shortly.
Plastics, and furnishings and bedding remained the biggest product classes in China-origin imports, representing 14% and 13.3% of the overall, respectively. Equipment and electrical equipment mixed for 17.6%, whereas toys and sporting items accounted for 9.9%.
Attire, made-up textiles and footwear collectively represented 10.7% of August China-origin import quantity.
Among the many China-origin commodity teams displaying year-over-year development, articles of iron or metal rose 30.5%, glass and glassware elevated 29.1%, and plastics climbed 6.9%. Equipment imports declined 9.8% from August 2025, whereas furnishings and bedding fell 5%.
Sourcing development extends past China
The report discovered import development was broadly distributed throughout main provider international locations.
The highest 10 international locations of origin collectively elevated U.S.-bound container quantity by 61,735 TEUs, or 3.5%, from July. Vietnam recorded the biggest month-over-month acquire, rising 14,545 TEUs, or 5.2%. Thailand elevated 11,633 TEUs, or 10.4%, whereas Indonesia rose 11,198 TEUs, or 19.5%.
China added 11,188 TEUs from July. Germany elevated by 5,195 TEUs, South Korea by 4,303 TEUs and Hong Kong by 2,222 TEUs. Italy and Taiwan additionally posted smaller features. India was the one top-10 sourcing nation to say no, falling 926 TEUs, or 0.8%.
In contrast with August 2025, the highest 10 sourcing international locations collectively added 41,482 TEUs, a 2.3% improve.
China produced the biggest year-over-year quantity acquire, rising 14,795 TEUs. Thailand elevated by 12,260 TEUs, Vietnam by 9,878 TEUs, Hong Kong by 8,493 TEUs, Indonesia by 5,375 TEUs, South Korea by 4,545 TEUs and Germany by 4,641 TEUs.
These features greater than offset declines from India, the place imports fell 16,034 TEUs, or 12.8%, and Taiwan, the place volumes declined 2,572 TEUs, or 4.5%. Italy was primarily unchanged 12 months over 12 months.
Commerce dangers cloud outlook
The August import surge occurred in opposition to a backdrop of rising supply-chain uncertainty.
Operational situations across the Strait of Hormuz remained risky on the finish of August. Reserving suspensions and decreased operations in components of the Higher Gulf have required some carriers and cargo pursuits to think about different land-bridge routings, non permanent storage preparations and specialised empty-container return procedures.
For U.S. importers, the direct publicity consists of increased transportation prices, decreased schedule reliability and potential disruption to vitality and industrial-input provide chains linked to the Persian Gulf area.
Tariff coverage additionally stays a cloth landed-cost consideration. Part 301 tariffs launched July 24 apply extra duties throughout quite a few buying and selling companions, typically starting from 10% to 12.5%, though charges, exemptions and caps differ by nation and product. Present Part 232 duties and China-related Part 301 measures add to the necessity for importers to evaluate responsibility publicity on the particular person Harmonized System code stage.
Individually, Panama Canal transit capability tightened in early September after below-expected precipitation within the space watershed. The Panama Canal Authority decreased each day Neopanamax availability to 9 slots and Panamax availability to 25 slots starting Sept. 3, with Panamax capability scheduled to fall additional to 23 slots on Sept. 15.
The modifications might have an effect on all-water Asia providers shifting to East and Gulf Coast ports, notably for vessels that don’t maintain secured transit reservations and should face longer ready instances.
Safety dangers within the Crimson Sea additionally stay elevated following renewed Houthi missile and drone assaults in opposition to Saudi vitality and financial services close to Jazan on the Crimson Beach. On the similar time, main carriers proceed to push the return of scheduled providers on the Suez Canal route and away from longer diversions round Africa.
Why it issues: August’s efficiency signifies that U.S. import demand has remained sturdy at the same time as cargo homeowners confront a rising set of coverage, routing and working dangers.
Learn extra articles by Editor right here.
Learn extra:
Houthi features deepen danger as carriers restore Crimson Sea providers
Nearly 1 million TEUs in new document for this U.S. container gateway
SC Ports, Norfolk Southern broaden intermodal entry to Huntsville
BNSF, CPKC, and CSX to request broad entry to a mixed UP-NS community
Summer time wanes however railfreight stays scorching
The publish U.S. container imports climb 3.8% to 2.6 million TEUs, third highest month-to-month stage appeared first on BigRig.