
With a rebound within the freight market anticipated to have commenced lengthy earlier than the tip of 2025, the inevitable query amongst analysts and observers is: what occurred?
That was the main focus of the November State of Freight webinar Tuesday, with BigRig’ strategic analyst John Paul Hampstead becoming a member of SONAR’s head of freight market intelligence Zach Strickland to take up the difficulty. BigRig and SONAR CEO Craig Fuller sat out the November webinar, with Hampstead taking his place.
One of many culprits was recognized shortly within the dialogue between Hampstead and Strickland: a turndown in demand. That was one of many 5 takeaways from the November dialogue.
They’re not shopping for what carriers are promoting
Carriers promote capability. Strickland and Hampstead reviewed information in SONAR’s Outbound Tender Quantity Index (OTVI) and it reveals that demand for that capability is mushy by any measure.
“The tender quantity index will not be very spectacular at this level,” Strickland mentioned, pointing to “the massive dip.” He mentioned quantity is down about 11% from this level within the calendar final 12 months although final 12 months at this level, the OTVI was taking a sudden counterseasonal downturn.
A current upturn within the OTVI was famous by Strickland, however he mentioned it was not “sturdy development.”
Hampstead mentioned many retailers could also be anticipating an “anemic or mushy demand or gross sales surroundings going ahead.” On condition that, “I feel that these retailers are completely satisfied to sort of burn off these inventories and allow them to run down,” he mentioned.
Demand, Hampstead mentioned, “is de facto what’s holding the truckload market again.”
What the rejection index is saying
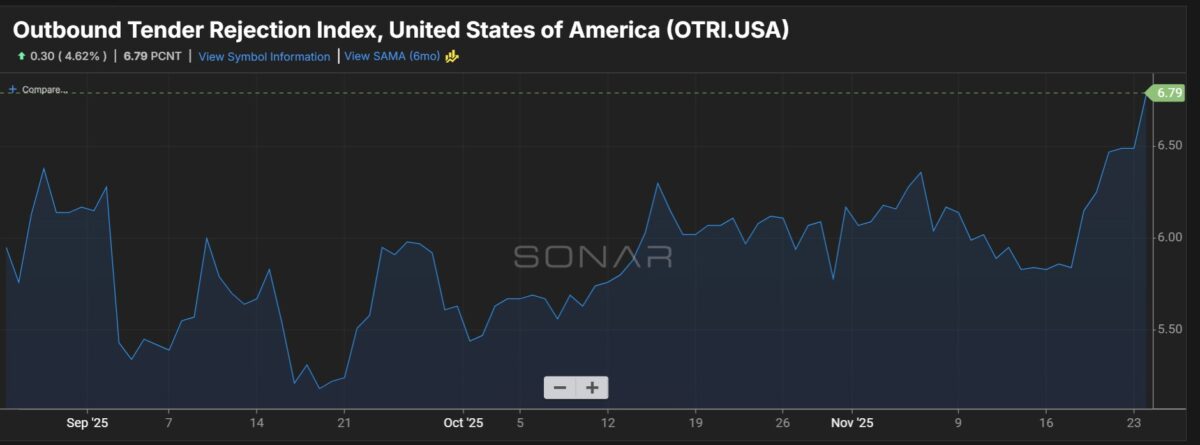
The counterpart to the OTVI is the Outbound Tender Rejection Index (OTRI). It’s a measure of capability and Strickland famous it’s stronger…however not by so much.
The rejection price has been rising, standing Tuesday at 6.79%. Final 12 months right now, Strickland famous, it was about 6.5%. “We’ve had this incremental tightening of capability that most individuals wouldn’t have felt, or they didn’t really feel it, as a result of it’s not occurring shortly,” Strickland mentioned. A distinction of that magnitude over a 12 months is “basically nothing,” he mentioned. “It has been slowly getting greater, so these will increase are simply not simply felt as a lot.”
Charges turning greater
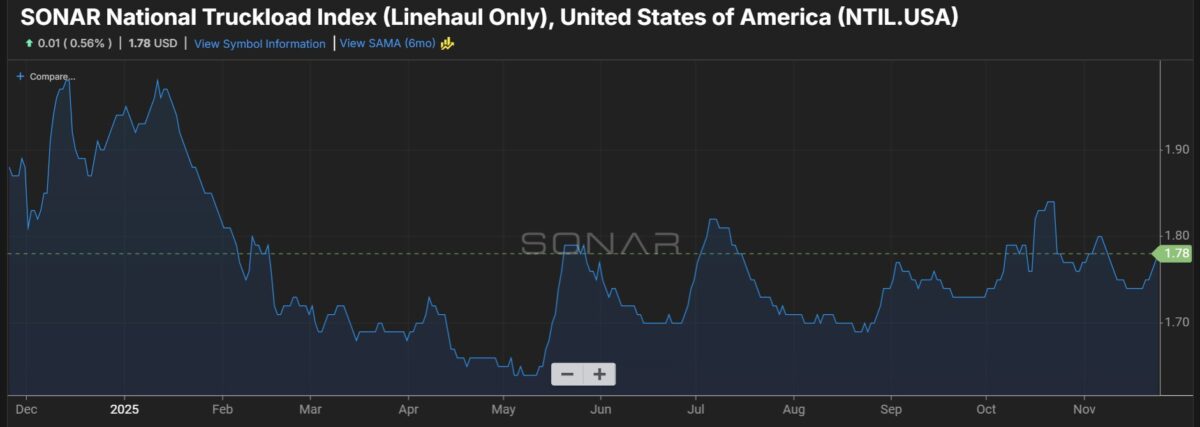
Though it hasn’t occurred but, Strickland mentioned spot charges are an space the place “lots of people count on issues to essentially take off.” Current motion has seen an upward transfer in SONAR’s NTIL, the Nationwide Truckload Index (Linehaul Solely),
Hampstead mentioned information from the OTVI means that there was extra long-haul enterprise not too long ago, and that tends to push down the speed per mile calculations.
However the newest strikes have been upward. When all the pieces is put collectively–the current small upturn in rejection charges and the upper NTIL numbers–”it tells you that there was a sluggish burn of capability leaving, and that even in a weak demand surroundings, issues are nonetheless tightening,” Hampstead mentioned.
As Strickland identified, plenty of carriers want that assist. “A variety of these operators are mainly simply shedding cash to remain alive,” he mentioned. “Their working ratios are above 100 which signifies that if it’s 101, you’re shedding a penny for each greenback you spend on shifting freight.”
Renewed deal with regulation
One of many arguments for tightening capability is a multi-pronged method towards tighter regulation coming from the states and from the Federal Motor Service Security Administration.
Past the crackdown over English language proficiency, Hampstead mentioned a visit by the listing of registered coaching suppliers who train the pipeline of recent truck drivers has quite a few attention-grabbing addresses, “like random Baptist church buildings, PO bins and folks’s flats. They’re clearly not offering coaching.”
“I feel plenty of that may be cleaned up,” Hampstead mentioned. “I feel there are extra kinds of vectors of assault that this administration is utilizing to assist clear up the kind of shadier finish of the spot market.”
Hampstead additionally mentioned the difficulty of dealer legal responsibility earlier than the Supreme Court docket might lead 3PLs to ramp up even better vetting of the carriers they selected. “It will put strain on brokers and their insurers to essentially perceive who they’re working with,” Hampstead mentioned.
Crackdown on ELDs
Hampstead cited one other space of regulatory push that has by no means been a number one focus of regulatory concern however is beginning to transfer up the charts: the FMCSA crackdown on ELDs, eradicating the company’s seal of approval from an rising variety of them.
The issue with ELDs offered by shady operators is that they are often simple to edit and manipulate, permitting a driver to exceed the traditional Hours of Service guidelines. That provides to capability. Taking them out of the market might work to tighten it. FMCSA has reported that this 12 months, it has revoked 24 ELDs, which it says is the very best quantity since ELD enforcement started in 2018.
“There are many dangerous ELD suppliers that change folks’s hours of service and allow them to kind of run illegally,” Hampstead mentioned. “These are lastly getting cracked down on, they usually’re eradicating bunches of suppliers each week. So I feel that may even are inclined to tighten capability within the spot market.”
Extra articles by John Kingston
A ‘jobs apocalypse’: panel at Trimble eyes AI’s future in logistics
Doubtless 1st AB5 trucking enforcement motion in California snags 3 firms
Trucking takeaways from Trimble: quantity down, driver inhabitants sliding
The submit State of Freight takeaways: sagging quantity, however capability tightening a bit appeared first on BigRig.