
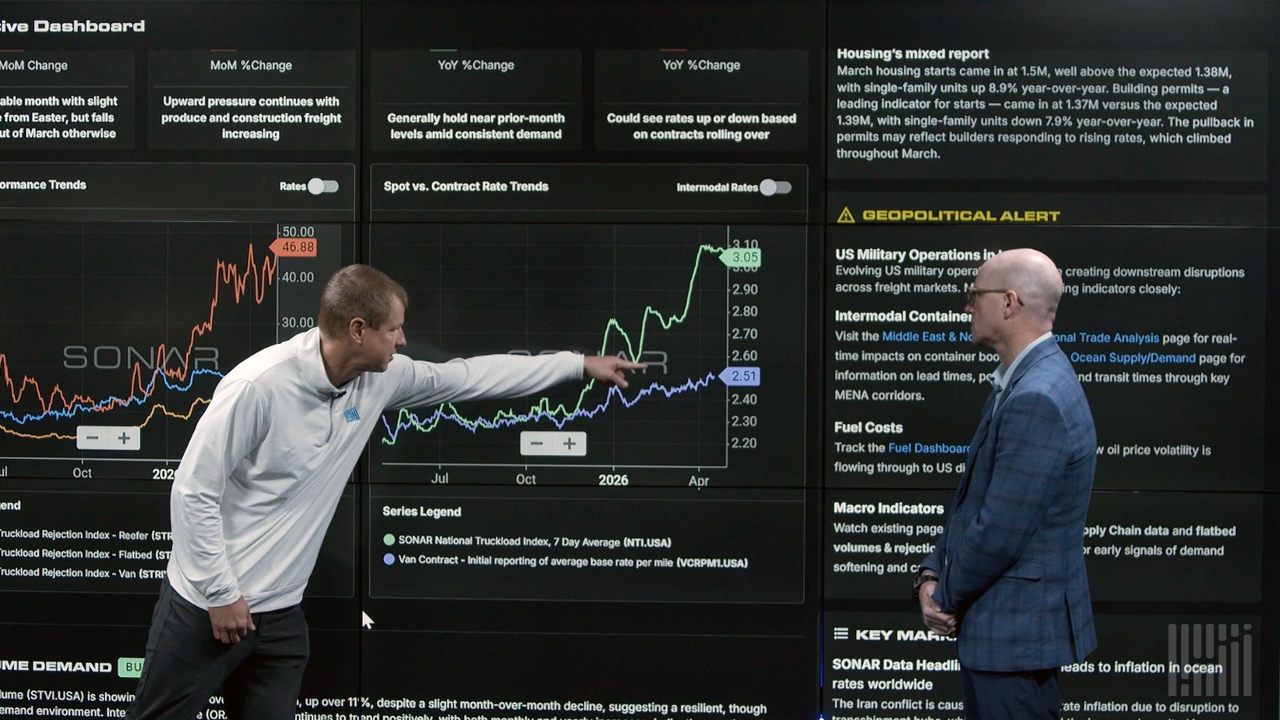
The April installment of the State of Freight webinar, hosted by BigRig CEO Craig Fuller and Head of Freight Market Intelligence Zach Strickland, pointed to a freight market that continues to be structurally tight—whilst seasonal softness and macro uncertainty cloud near-term visibility.
From geopolitical disruptions within the Center East to imminent enforcement occasions and summer season demand patterns, the dialogue highlighted a market transitioning from restoration right into a extra sturdy tightening cycle. Listed here are 5 key takeaways:
Iran battle driving gasoline volatility, however not derailing demand
Fuller mentioned the continuing battle in Iran is having a transparent affect on gasoline markets, although the broader freight economic system stays resilient.
“All of it’s tied to Iran… excessive oil costs are an element at Iran… however there’s nothing in any of the info that claims that larger gasoline prices… is sapping the U.S. economic system,” Fuller mentioned
Strickland famous that diesel volatility has been reactive to geopolitical developments, particularly across the Strait of Hormuz.
“We noticed this beautiful important spike in retail diesel… after which as we began to see the top of the navy battle… the worth of diesel got here down,” Strickland mentioned.
Fuller, emphasizing that gasoline prices alone usually are not dictating freight pricing energy, mentioned the “tightness in capability permits motor carriers to have pricing energy… not essentially diesel.”
Strickland added that carriers are nonetheless recovering gasoline prices by way of charges in a tightening surroundings. “In the event you have a look at what the charges are… you’ve been in a position to get better all of that and doubtlessly extra,” he mentioned
April: inflection level or seasonal “pace bump”?
Each executives pushed again on the concept that April’s softer tendencies sign a reversal.
“April has been… simply type of a sideline,” Strickland mentioned. “It’s not up and to the precise the best way we noticed it in March.”
Fuller countered that the market stays far stronger than year-ago ranges.
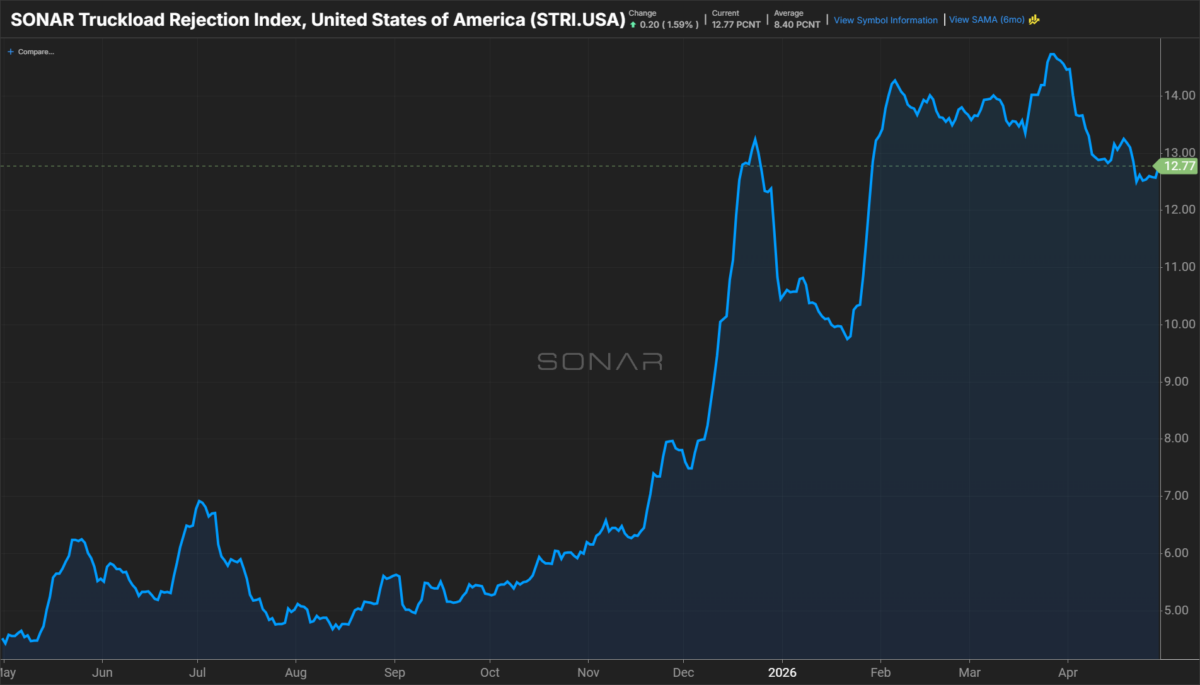
“We’re speaking about rejection charges… at 12.7%… these are ranges that we haven’t seen in years,” Fuller mentioned.
He additionally pointed to stronger macro alerts underpinning freight. “You’re beginning to see broader financial information… indicating a lot stronger exercise than most individuals anticipated.”
Strickland framed April as a typical seasonal trough reasonably than a turning level.
“April is traditionally a weak month… you find yourself in Might with a large acceleration,” Strickland mentioned.
Roadcheck may tighten already constrained capability
Trying forward, each warned that the upcoming CVSA Worldwide Roadcheck may meaningfully disrupt capability.
“We’re going to see capability come off the roads… greater than typical,” Fuller mentioned.
He added that stricter enforcement and compliance scrutiny are already influencing driver habits.
“Drivers know that the DOT is getting directives to actually crack down… so I feel we’re going to see extra capability taken off the highway,” Fuller mentioned.
Strickland mentioned the affect could possibly be amplified by an already tight market, including “there may be little or no extra capability… so the market is way more delicate.”
Fuller expects rejection charges to spike through the enforcement interval.
“We’ll get into the 16%–17% vary for every week,” he mentioned.
Summer time demand alerts level to stronger freight cycle
Each executives highlighted robust indicators heading into peak summer season transport.
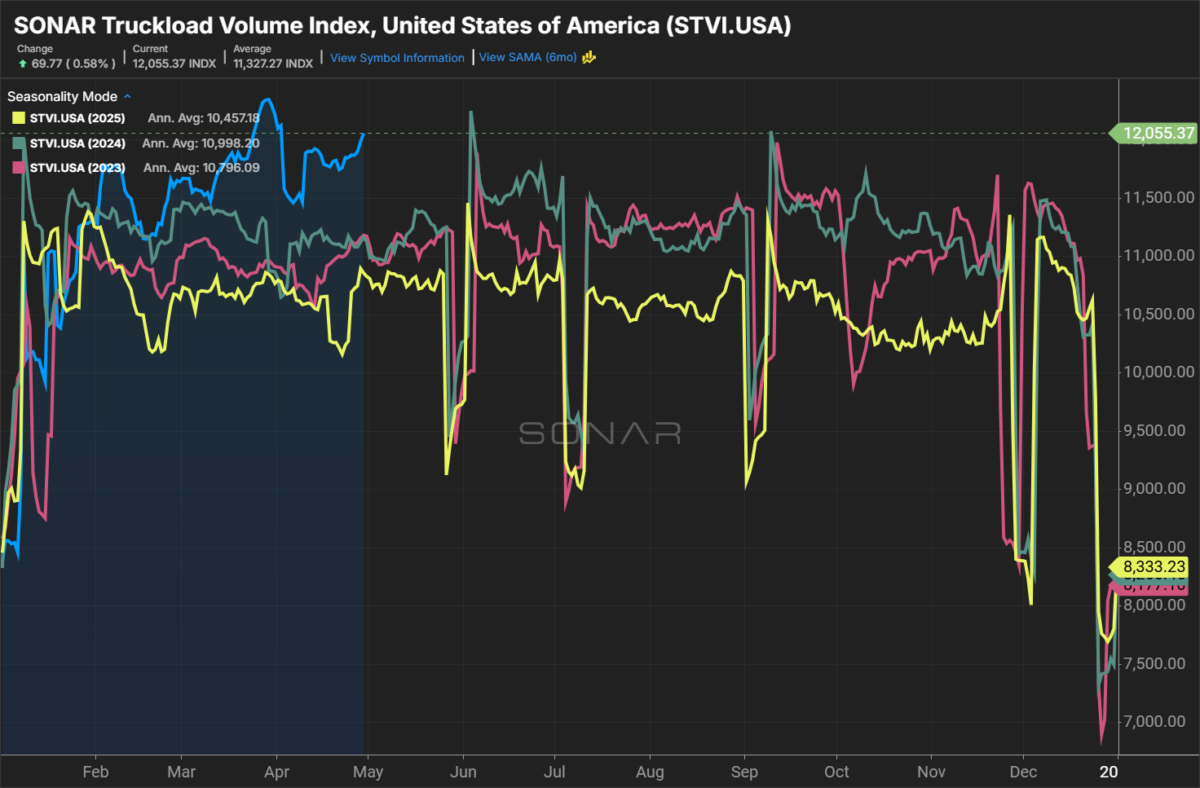
“Demand has gotten stronger… and we’re seasonally about to enter a a lot stronger demand cycle,” Strickland mentioned.
Fuller pointed to structural drivers past conventional retail.
“June is the most important month of the 12 months… you’ve produce, building, industrial manufacturing—all coming collectively,” Fuller mentioned.
He additionally emphasised that industrial exercise—not client retail—is driving the present cycle. “What’s been driving this market shouldn’t be client retail… it’s largely industrial,” Fuller mentioned.
Strickland added that volumes are already displaying energy — “volumes are up 11% 12 months over 12 months… in all probability 12% to 13% now.”
Dangers and alternatives shaping the highway forward
The webinar closed with a have a look at structural shifts that might reshape the freight market.
Fuller pointed to regulatory and authorized dangers, together with dealer legal responsibility and compliance crackdowns.
“That is going to be in all probability the most important story of the summer season… it’s going to fully change the best way brokers function,” Fuller mentioned.
He additionally highlighted capability constraints tied to regulation, including “you’re speaking concerning the web affect… as a lot as 600,000 to 800,000 drivers.”
Strickland famous that charge strain is already constructing.
“We’re already at a few 10% improve… and we’re going to see that develop all year long,” Strickland mentioned.
Fuller mentioned the market has clearly moved previous the downturn.
“There isn’t any freight recession proper now… we’re clearly finished with it,” he mentioned.
The publish State of Freight: Freight recession ‘over’ as demand builds into summer season appeared first on BigRig.