
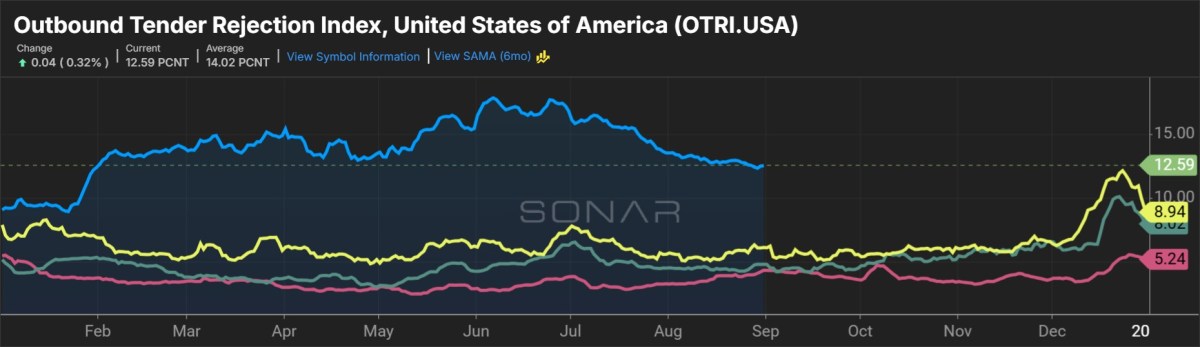
U.S. manufacturing exercise remained supportive of freight demand for an eighth straight month in August, however by a lesser diploma than in July. Progress cooled for some key parts like new orders, however the slowdown could possibly be tied to firms pulling ahead inventories forward of tariff implementations earlier this summer time.
A survey of producing provide executives returned a 54.6 studying for the current month, which was 1 share level beneath July (the best stage recorded since Might 2022). Economists had been calling for a 55.2 studying in August.
A studying above 50 for the Institute for Provide Administration’s Manufacturing PMI alerts growth, whereas one beneath 50 signifies contraction. A sustained stage above 47.5 alerts the general financial system is rising. The August studying was per annualized actual GDP progress of two.4%, the Tuesday report stated.
The brand new orders index—an indicator of future exercise—additionally expanded for an eighth consecutive month. Nonetheless, the 53.7 stage captured in August was 3 factors beneath July. The backlog of orders dataset (51.8) remained constructive, however got here in 3.2 factors decrease sequentially as manufacturing (58.3) remained elevated.
Demand sentiment round information orders was much less optimistic with a 2-to-1 ratio of positive-to-negative feedback in comparison with 3.5-to-1 in July.
Prospects’ inventories (42.8) remained “too low,” however the index was up 2.1 factors sequentially. Manufacturing employment (51.2) turned constructive in July for the primary time in 33 months and remained so in August.
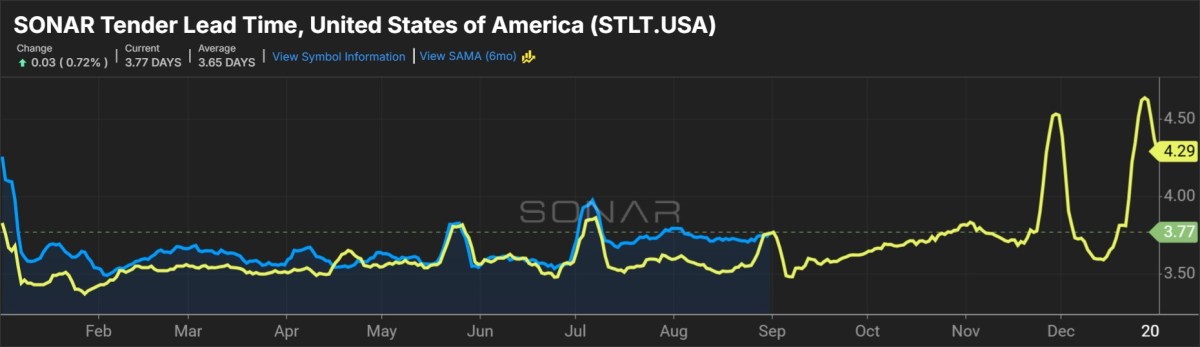
Transportation capability remained tight in August, in response to the Logistics Managers’ Index, which was additionally revealed Tuesday. The information confirmed a 40 studying for the month, which remained deep into contraction territory, however at a contraction price that was 11.6 factors slower than in July.
The ISM’s provider deliveries dataset, which measures supply occasions to manufacturing services, confirmed a slowing in deliveries and potential provide chain constraints for a ninth straight month. The 59.3 studying was up 40 foundation factors sequentially. (This ISM subindex is the one one that’s inverted.)
Of the 14 manufacturing industries tracked, “no industries reported that provider deliveries had been sooner in August in comparison with July.”
Inflation was flagged as a key concern amongst respondents, with the costs index (71.1) remaining elevated, however stage with July. The most recent studying implies “uncooked supplies costs elevated for the twenty third straight month.” Respondents reporting greater costs fell 4 factors to 46.2%.
Total, respondent sentiment was 42% constructive and 58% adverse for the month. Pricing volatility was the most important concern cited within the adverse feedback.
Public less-than-truckload carriers will report August tonnage tendencies within the coming days. The economic financial system sometimes accounts for roughly two-thirds of LTL income.
Why it issues? The ISM dataset offers key macroeconomic indicators that straight influence logistics, procurement and capability planning.
Extra BigRig articles by Todd Maiden:
- Transportation capability contraction slows in August
- Averitt expands logistics community with Jackson, Mississippi, facility
- Dealer RXO sees TL spot price surge lengthen into Q3
The submit August’s manufacturing PMI dips to 54.6; provide chain constraints persist appeared first on BigRig.